

Blogs
Tire Changers Market 2026: Why 6.8% CAGR and Asia Pacific’s Scale Shift Everything
By PW Consulting, 2026-09-21
Beyond the Service Bay: Strategic Shifts Reshaping the Tire Changers Market Through 2032
Market Trajectory: From Incremental Growth to Structural Expansion
The global tire changers market is undergoing a transformation that extends well beyond routine equipment replacement cycles. Valued at approximately 1,471 million USD in 2025, the market has expanded at a steady pace since 2020, when it stood near 1,135 million USD. This growth reflects not only broader automotive service activity but also a fundamental shift in how service centers, fleets, and independent shops approach wheel maintenance efficiency, safety compliance, and operational throughput.
Projecting forward through 2032, the market is expected to surpass 2,300 million USD, supported by a compound annual growth rate of 6.8 percent. The trajectory suggests a market that is maturing but still possesses meaningful expansion headroom, particularly as regional service infrastructure develops, vehicle fleets age, and new equipment configurations address increasingly complex rim and tire profiles. The growth is not uniform across all segments, however, and the divergence in adoption patterns points to strategic opportunities for players who can align product capabilities with evolving service demands.
Worldwide Tool Changers Market
Core Challenges at the Inflection Point
Several interconnected challenges are redefining how tire changer manufacturers, distributors, and end users navigate the market. These are not temporary friction points but structural shifts that will influence equipment selection, pricing dynamics, and competitive positioning for years to come.
First, tightening safety and operational compliance requirements are reshaping procurement criteria. Vehicle maintenance environments, particularly those supporting commercial fleets and heavy-duty operations, face heightened expectations around machine guarding, turntable accessibility, and workstation hazard mitigation. Industry guidance continues to emphasize that equipment must meet or exceed established safety standards to reduce compliance exposure and minimize unplanned downtime. For service operators, this elevates the importance of equipment that integrates protective design features without compromising speed or ease of use.
Second, shifting trade policies and import exposure are introducing volatility into equipment sourcing and cost structures. Recent policy movements have placed renewed attention on the origin of automotive service equipment, affecting pricing assumptions and supply continuity for buyers who rely on cross-border procurement. The change is prompting service businesses and manufacturers alike to reassess supply chain dependencies, localize component sourcing where feasible, and evaluate total cost of ownership rather than upfront price alone.
Third, the evolving tire and wheel landscape is placing new technical demands on change equipment. As service centers encounter wider variety in rim diameters, lower-profile tires, and mixed passenger and commercial workloads within the same bay, equipment that once performed adequately for generalized use is increasingly expected to handle more specialized applications. This is driving interest in flexible mount configurations, enhanced bead-breaking performance, and designs that reduce manual force requirements while maintaining operator control.
Key Drivers Accelerating Market Evolution
Technology Innovation and Equipment Differentiation
Innovation in tire changer design is moving beyond incremental feature additions toward more integrated, ergonomic, and application-specific solutions. A clear trend is the development of hybrid mount systems that blend the speed and consistency of automatic or semi-automatic operation with the adaptability of leverless or swing-arm configurations. These systems address a practical service center challenge: reducing changeover time while limiting tire and rim damage risk on challenging assemblies.
PW Consulting
Recent equipment introductions highlight this direction. One major engineering provider expanded its table-top and center-clamp offerings with models featuring hybrid leverless mount heads, enhanced torque capabilities, and integrated inflation systems designed to streamline the full change cycle. Additional center-clamp and swing-arm combinations have focused on merging the advantages of both configurations, giving operators more flexibility when working with difficult bead seats or non-standard rim geometries. In parallel, other manufacturers have refreshed product platforms with emphasis on shop efficiency, stronger jaw configurations for commercial wheel sizes, and simplified controls that support faster operator training.
The practical implication is that equipment performance is increasingly being measured by repeatability, operator safety, and the ability to handle a broader range of tire and wheel profiles without frequent re-tooling or manual intervention. For manufacturers, this creates a competitive environment where differentiation stems less from basic functionality and more from how well the equipment fits specific shop workflows.
Regulatory and Safety Standards as a Market Shaping Force
Regulatory expectations are becoming a more prominent element of equipment selection and procurement strategy. Safety guidelines relating to machine guarding, turntable edge protection, and workstation hazard control continue to influence how service centers evaluate tire changers, especially in commercial and fleet maintenance environments. Equipment that supports compliance through integrated guarding, clear operational zones, and reduced exposure to pinch or trip hazards is gaining preference in risk-conscious buying environments.
This regulatory emphasis interacts with operational realities in fleet service. Out-of-service criteria and downtime sensitivity make reliability and consistency important procurement considerations, not only from a safety standpoint but also from a logistics perspective. When maintenance interruptions carry consequences for fleet availability, equipment that supports predictable cycle times and reduces manual variability becomes more valuable. In this context, regulatory alignment is not simply a compliance checkbox; it is increasingly part of a broader operational resilience discussion.
Demand-Side Shifts in Service Behavior
Service behavior is shifting on both the passenger and commercial sides, though for different reasons. Passenger vehicle service demand continues to benefit from growing vehicle parc activity, seasonal tire change programs, and a broader emphasis on preventive maintenance. At the same time, commercial vehicle service demand is being shaped by fleet maintenance requirements, uptime pressures, and the need to service larger and sometimes mixed wheel configurations efficiently.
These demand patterns are influencing the relative attractiveness of different equipment categories. Shops handling higher passenger vehicle volumes tend to prioritize fast change cycles, consistent mounting performance, and space-efficient equipment footprints. Commercial-focused operators place greater weight on robustness, bead-breaking capability, and compatibility with heavier or larger-diameter wheels. As service centers increasingly manage blended workloads, demand is rising for equipment that can adapt across these contexts without forcing separate line investments for each application type.
Cost Structure and Supply Chain Realignment
Cost dynamics are being reshaped by both input material considerations and broader sourcing strategy changes. Equipment that relies heavily on durable structural materials such as steel for frames and load-bearing components presents a different cost and longevity profile than lighter or fully imported alternatives. In an environment where procurement teams are more attentive to lifecycle durability, serviceability, and supply continuity, the emphasis is shifting toward equipment that offers predictable maintenance demands and resistance to premature wear.
At the same time, sourcing complexity is encouraging manufacturers and distributors to think more strategically about regional production footprints, component availability, and the balance between import dependency and localized assembly or fabrication. For buyers, this translates into greater scrutiny of supplier reliability, spare parts access, and the longer-term economic implications of equipment selection beyond the initial purchase price.
Competitive Landscape: Positioning, Differentiation, and Structural Change
The tire changers market features a mix of established manufacturers with strong regional presence, specialized equipment providers, and firms leveraging broader automotive service portfolios. Competitive advantage is increasingly defined by product versatility, workflow integration, and the ability to support compliance and durability expectations while maintaining effective pricing and service support.
One U.S.-based engineering company has continued to consolidate attention around its tire changer line by introducing multiple product updates within a short period. Its recent launches have emphasized hybrid leverless mount heads, enhanced torque delivery, integrated inflation systems, and lower locking disc configurations. These updates illustrate a strategy centered on expanding the capability range of core platforms while addressing difficult tire and rim combinations that can slow traditional change processes. By positioning its products as adaptable across table-top, center-clamp, and swing-arm use cases, the company is reinforcing a message of workflow flexibility for service centers that need to accommodate varied tire and wheel profiles.
Another U.S. manufacturer has taken a different but complementary approach, emphasizing domestically designed and built equipment with strong structural component choices and feature enhancements aimed at commercial wheel sizes. Recent updates have included stronger jaw options for larger commercial diameters, refreshed shop-facing branding, and product presentations tied to professional service audiences. The emphasis on steel-intensive construction and application-specific jaw configurations signals a focus on durability and commercial service demands, an angle that resonates with buyers concerned about heavy usage cycles and long equipment life.
Additional competitors reflect the breadth of the landscape. Some firms concentrate on car, truck, and motorcycle applications with accessible professional-grade solutions, often pairing tire changers with complementary shop equipment to deliver more complete service bay packages. Others, particularly in Europe, have built reputations around integrated wheel service systems, combining tire changers with balancers and alignment-related equipment to support full-service workflows. Chinese manufacturers have also continued to participate in the market with automatic and touchless-style designs that target efficiency and specialized mounting needs. Italian equipment makers remain notable for superautomatic and standard configurations directed at garages and service centers, while other established suppliers focus on variable-speed direct-drive designs or rim-clamp models tailored to repair shop use.
The overall competitive structure shows moderate concentration, with leading firms holding meaningful share while leaving substantial room for regional specialists and application-focused entrants. This fragmentation is likely to persist in the near term, but the nature of competition is shifting. Rather than competing only on basic equipment capability, manufacturers are increasingly differentiating through product families that span multiple mounting styles, integrated shop-system positioning, and feature sets that respond directly to compliance, durability, and operator efficiency expectations.
Market evolution is also being shaped by the interplay between established players and new product introductions that blur traditional category lines. Hybrid configurations, enhanced commercial wheel compatibility, and integrated shop efficiency features suggest that the boundary between fully automatic, semi-automatic, and manual-oriented equipment is becoming more flexible in practice. Buyers are increasingly evaluating platforms based on the operational outcomes they enable rather than strict equipment classification.
Tire Market
Future Trends Shaping the Next Three to Five Years
Trend One: Convergence Toward Flexible, Application-Responsive Platforms
Over the next several years, demand is likely to continue favoring tire changers that can handle a wider mix of tire and wheel profiles without requiring multiple dedicated machines. Hybrid mount systems, adaptable jaw or duckhead configurations, and designs that support both passenger and light commercial use will become increasingly important in mixed-workload service environments. This trend creates opportunity for manufacturers that can offer scalable platforms and for service centers that can consolidate equipment while expanding service coverage. It also introduces a risk: platforms that promise flexibility but sacrifice reliability, ease of training, or maintenance simplicity may struggle to retain buyer confidence.
Trend Two: Compliance, Safety, and Uptime as Core Purchase Criteria
Safety and regulatory alignment will continue moving from a secondary consideration to a primary procurement driver, especially in commercial fleet service and higher-volume maintenance environments. Equipment selection will increasingly account for guarding design, workstation layout, operator exposure reduction, and consistent cycle performance that supports downtime management. The commercial opportunity lies in products and service packages that frame compliance and uptime as integrated benefits rather than separate features. The uncertainty lies in how standards, inspection practices, and enforcement expectations may further evolve, which could change the relative weight of specific equipment attributes over time.
Trend Three: Regional Sourcing, Cost Discipline, and Lifecycle Value Thinking
As equipment buyers become more attentive to sourcing exposure, long-term durability, and total cost of ownership, market dynamics will favor suppliers that can articulate clear lifecycle value and maintain predictable parts and service support. Domestic or regionally anchored production strategies, durable structural design, and transparent maintenance requirements may gain relative advantage in segments where operational continuity matters most. At the same time, import-dependent supply paths may face continued pressure from policy changes and buyer risk tolerance. The strategic opportunity is for manufacturers and distributors to build clearer value narratives around durability, service access, and supply reliability, while buyers benefit from more disciplined equipment evaluation frameworks.
Strategic Implications for Decision Makers
For manufacturers and product leaders, the near-term priority is to strengthen platform versatility without diluting reliability. Product strategies that combine hybrid mounting options, commercial wheel compatibility, and clear operator-safety design are well positioned to address the converging demands of passenger and commercial service environments. Equally important is the ability to support these products with dependable parts availability, service guidance, and a value proposition that extends beyond initial pricing. Companies that can connect product features to measurable shop outcomes—reduced change time, lower operator fatigue, fewer compatibility limitations, and stronger compliance support—will have a stronger footing in an increasingly outcome-driven buying environment.
For investors and strategic partners, the market offers opportunity in segments where durability, compliance alignment, and mixed-application flexibility are gaining weight. Attention should be directed toward manufacturers with coherent product roadmaps, clear regional or supply-chain positioning, and the ability to serve both specialized and broad-service customers. Investment theses should account for the possibility that trade-policy exposure, raw material dynamics, and shifting procurement preferences may alter competitive advantages over time, making supplier resilience as important as product strength.
For procurement teams and service operators, equipment evaluation should move beyond headline specifications and incorporate workflow fit, safety design, commercial wheel compatibility, and long-term serviceability. The most effective purchasing decisions will increasingly reflect how equipment supports bay productivity, compliance readiness, and the ability to handle a broader mix of tire and wheel service demands without unnecessary specialization overhead. Framed this way, tire changers become not just a maintenance tool but part of a broader operational efficiency and risk management strategy.
Detailed segmentation data, company-level capability mapping, and application-specific demand patterns can materially sharpen these decisions. For organizations seeking a deeper view of regional dynamics, product-category shifts, and competitive positioning across the tire changers market, the full PW Consulting research report provides a more granular foundation for planning and investment prioritization.
For detailed analysis of this topic, please visit the official page: Tire Changers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Oscilloscope Market 2032: How 6.95% CAGR and 72.3% CR3 Reshape Competition
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Oscilloscope Market
The oscilloscope market is undergoing a structural transformation driven by escalating signal complexity, the proliferation of high-speed digital architectures, and a widening gap between traditional benchtop instrumentation and software-defined measurement workflows. As electronic systems push into multi-gigabit bandwidth regimes and real-time diagnostics become embedded in product development cycles, oscilloscopes are evolving from standalone capture devices into integrated analysis platforms. This shift is reshaping demand patterns, competitive positioning, and investment priorities across the test and measurement ecosystem.
Market Overview and Core Challenges
Commercial Trajectory and Structural Dynamics
The global oscilloscope market has demonstrated steady expansion over the past half-decade, with revenue crossing 200 billion dollars in recent years and continuing its upward trajectory into the mid-twenties. The market's compounded annual growth rate of approximately 6.95 percent through the forecast horizon reflects a maturing yet still expanding category, where incremental adoption is increasingly tied to advanced capability upgrades rather than base-level replacement. Revenue distribution across form factors reveals a dominant benchtop foundation, complemented by a rapidly growing portable segment and a substantial PC-based footprint that underscores the industry's pivot toward software-centric workflows. Bandwidth segmentation highlights a concentration of demand in the mid-range spectrum, while the sub-500 MHz tier remains a steady volume driver for general-purpose applications. Higher bandwidth categories, particularly those exceeding 4 GHz, represent a smaller but strategically critical slice tied to high-speed digital design, signal integrity validation, and next-generation communication testing. Industry-level demand spreads across automotive and transportation, IT and telecommunications, consumer electronics, aerospace and defense, medical and life sciences, and a diversified remainder, reflecting the instrument's cross-sector relevance.
The market is characterized by pronounced concentration, with a small group of established players commanding a substantial share of global revenue. This consolidated structure has historically reinforced premium pricing, long product lifecycles, and deep application-specific support. However, the same concentration also creates pressure points as demand fragments across more diverse testing scenarios and price-sensitive segments expand in emerging manufacturing hubs.
Key Challenges and Inflection Points
The industry faces several intertwined challenges that are redefining how manufacturers, buyers, and investors evaluate opportunity. First, the boundary between hardware performance and software capability is blurring. Advanced waveform analysis, automated compliance testing, and AI-assisted interpretation are becoming differentiators that matter as much as raw bandwidth or sampling rate. Companies that continue to compete primarily on analog specifications risk ceding ground to platforms that deliver faster time-to-insight and tighter integration with design environments.
Second, supply chain and component availability for high-performance analog front-ends, precision clocks, and high-speed digitizers remain sensitive to geopolitical and semiconductor cycle dynamics. Leading manufacturers are navigating longer validation cycles and elevated lead times for critical subsystems, which affects time-to-market for next-generation series and complicates capacity planning in high-growth regions.
Third, the purchasing behavior of engineering teams is shifting. Design organizations increasingly favor instruments that support bench-to-field workflows, remote collaboration, and seamless data export into simulation and verification tools. This demand-side evolution is pressuring incumbents to rethink channel strategies, service models, and the balance between entry-level volume products and high-margin specialized systems.
Key Demand Drivers
Technology Innovation and Capability Gaps
The most consequential driver is the accelerating pace of signal complexity in modern electronic architectures. High-speed serial links, advanced packaging, RF-intensive designs, and mixed-signal integration are pushing test requirements beyond traditional capture capabilities. In this environment, oscilloscopes are being asked to deliver higher waveform capture rates, deeper memory, lower noise floors, and more sophisticated analysis libraries. The recent emphasis on real-time instruments tailored for high-speed digital and compliance testing illustrates how vendors are aligning product roadmaps with these technical demands. Simultaneously, the introduction of compact mixed-signal platforms designed for seamless bench-to-field workflows signals a broader push toward portability, multi-channel flexibility, and field-deployable diagnostics without sacrificing analytical depth.
A second technology-related driver is the integration of intelligent analysis features. Automation of measurements, pattern recognition, and guided troubleshooting are reducing the dependency on highly specialized operators and enabling faster iteration in development cycles. This trend is particularly relevant for teams working on 5G-related validation, quantum computing instrumentation, and advanced signal integrity applications, where the volume and complexity of captured data make manual interpretation impractical.
PW Consulting
Policy and Regulatory Environment
Regulatory and compliance requirements are shaping demand in subtle but persistent ways. Automotive safety standards, emissions testing mandates, and industry-specific certification frameworks are expanding the scope of required validation, especially in sectors where electronic control units, power Electronics, and communication modules must meet rigorous performance thresholds. In aerospace and defense, traceability, measurement confidence, and long-term supportability continue to favor established instrumentation with documented calibration and verification pathways. These requirements create a steady baseline of demand for compliant, well-supported platforms, while also raising the barrier for new entrants that lack institutional credibility or comprehensive service networks.
Demand-Side Shifts in Engineering and Manufacturing
Engineering organizations are under increasing pressure to shorten design cycles and reduce rework. The adoption of mixed-signal architectures, broader use of embedded sensors, and tighter integration between hardware and software teams are driving demand for instruments that can support multiple use cases without requiring separate toolchains. Portable and PC-based formats are gaining relevance in environments where measurements must be taken outside traditional lab settings, including field commissioning, production line debugging, and remote diagnostics. At the same time, larger enterprises are prioritizing platforms that connect to enterprise data workflows, enabling measurement results to feed directly into quality systems, design reviews, and compliance documentation.
Supply Chain and Cost Structure Evolution
Cost dynamics are increasingly influenced by the balance between performance differentiation and affordability. In entry-level and mid-range segments, competitive pressure is intensifying as manufacturers expand feature sets that were once reserved for higher tiers. This compression is prompting a recalibration of pricing strategies and encouraging a segmentation approach in which value is created through application-specific bundles, software subscriptions, and support services rather than hardware alone. On the supply side, the need for high-quality analog components and precision fabrication continues to favor scaled manufacturers with strong procurement relationships and multi-sourced component strategies. Companies that can maintain stable production while introducing differentiated analysis capabilities are better positioned to protect margins in a more crowded competitive field.
Competitive Landscape and Leading Strategies
Strategic Positioning of Core Players
The competitive environment is shaped by a mix of established multinational manufacturers and focused regional players, each pursuing distinct value propositions. One U.S.-based leader has built a strong identity around high-performance oscilloscopes for high-speed digital, 5G, and quantum computing applications, reinforced by AI-assisted analysis capabilities. Its recent launch of a real-time oscilloscope series targeting high-speed digital and compliance testing demonstrates a strategy centered on pushing the performance envelope while embedding smarter interpretation tools. The emphasis on advanced compliance workflows indicates a deliberate move toward use cases where measurement accuracy, repeatability, and regulatory alignment carry substantial commercial weight.
A second U.S. incumbent is widely recognized for digital phosphor and mixed-signal oscilloscopes that extend into high-frequency ranges with advanced waveform analysis. Its introduction of a mixed-signal oscilloscope designed for bench-to-field workflows reflects an effort to bridge laboratory precision with field usability, a positioning that appeals to engineering teams seeking continuity across development, validation, and deployment environments. This approach underscores a broader strategic theme: reducing friction in measurement workflows rather than competing solely on specification sheets.
A German manufacturer has carved out a strong position with compact and entry-level oscilloscopes offering multiple channels and high waveform capture rates, particularly in general and automotive testing. Its focus on accessible multi-channel configurations suggests a strategy aimed at capturing volume in sectors where testing throughput and channel density are critical, while still maintaining a credible presence in performance-oriented applications. A U.S. specialist remains closely associated with high-bandwidth sampling oscilloscopes for signal integrity and high-speed testing, a niche that rewards deep domain expertise and application-specific optimization. A Japanese measurement company continues to emphasize precision test and measurement oscilloscopes for industrial and engineering applications, leveraging a reputation for reliability and long-tail support.
On the other side of the competitive spectrum, Chinese manufacturers are expanding their footprint in affordable digital oscilloscopes for bench and educational use, as well as high-resolution instruments for high-speed signal integrity testing. Their growth is closely tied to price competitiveness, feature densification at lower price points, and growing acceptance in cost-sensitive markets and training environments. A UK-based provider has focused on USB-based oscilloscopes for portable and PC-integrated signal capture, an approach that aligns with the broaderPC-based and portable momentum and serves users who prioritize integration simplicity and flexibility over standalone instrument form factors.
Market Evolution and Competitive Dynamics
Several structural dynamics are influencing how the competitive landscape is evolving. One is the tension between consolidation and segmentation. While the market remains concentrated at the top, demand is fragmenting across more application-specific requirements, form factors, and price points. This creates space for both specialized leaders and agile challengers, depending on the segment. High-performance and compliance-driven segments tend to reward established credibility and deep support ecosystems, while entry-level and mid-range segments are more contested and sensitive to feature-to-price ratios.
Multimeters Market
Another dynamic is the growing importance of software and services as sources of differentiation. As measurement workflows become more connected and analysis more automated, the value of an instrument increasingly depends on how well it fits into the broader engineering environment. Product launches that emphasize workflow continuity, advanced capture rates, and intelligent analysis suggest that leading manufacturers recognize software-defined value as a durable competitive advantage. At the same time, new entrants and regional players are using affordability and targeted feature sets to gain traction, particularly where procurement budgets and training needs prioritize accessible, versatile tools.
A third dynamic is geographic diversification of demand and supply. While mature markets continue to anchor high-value deployments, growth in Asia Pacific and other developing regions is expanding the addressable base for both premium and cost-effective instruments. This geographic spread is encouraging manufacturers to adapt product portfolios, service coverage, and channel strategies to local engineering practices and procurement norms.
Future Outlook for 2026–2032
Trend 1: Software-Defined Measurement and Intelligent Analysis Become Table Stakes
Over the next several years, the differentiator set for oscilloscopes will increasingly favor platforms that combine strong hardware foundations with software capabilities that accelerate interpretation and decision-making. AI-assisted analysis, automated compliance routines, and deeper integration with simulation, documentation, and quality systems are likely to become more standard across mid-range and high-end offerings. This trend opens commercial opportunities for vendors that can package analysis workflows as repeatable, auditable processes, and for buyers who can reduce engineering cycle time through better measurement-to-insight pathways. The risk is that software expectations rise faster than hardware roadmaps, creating mismatch risk for products that advertise intelligence without corresponding workflow maturity or data interoperability.
Trend 2: High-Speed Digital, Signal Integrity, and Compliance-Driven Demand Will Keep Pulling the High-End Forward
Demand for higher bandwidth, deeper capture, and more precise signal integrity validation is expected to remain a primary engine of premium segment growth. Applications in high-speed digital design, advanced communication testing, and specialized research environments will continue to reward instruments that can handle complex waveforms with low noise and high repeatability. Commercial opportunity here lies in bundled solutions that pair high-performance hardware with application-specific libraries, calibration support, and compliance-oriented documentation. The uncertainty is that the high-end pipeline is sensitive to component availability and validation timelines, which can cause uneven release cadences and temporary gaps between market demand and available capacity.
Trend 3: Form Factor Diversification Will Broaden the Addressable Use Case Set
Portable and PC-based oscilloscope formats are likely to continue gaining relevance as measurement moves beyond the lab and into field, production, and remote settings. Benchtop systems will remain central for high-performance and complex multi-channel work, but the broader market will increasingly value instruments that adapt to varied environments without sacrificing analytical rigor. This creates opportunities for manufacturers that can deliver flexible channel configurations, robust portability, and easy integration with PCs and enterprise tools. The risk is that form factor proliferation complicates product management and service coverage, especially for organizations trying to serve both centralized labs and distributed engineering teams with a unified portfolio.
Dermatoscope Market
Strategic Implications for Decision Makers
For Manufacturers and Product Leaders
Balancing performance leadership with workflow usability will be essential. Investing in analysis software, automated measurement packages, and seamless data export can strengthen stickiness and justify premium positioning, especially in high-speed digital, compliance, and signal integrity markets. At the same time, manufacturers should monitor the entry-level and mid-range segments closely, where feature densification and competitive pricing are reshaping buyer expectations. A clear segmentation strategy, supported by disciplined component sourcing and predictable release cycles, can help protect margins while preserving access to growth regions and application verticals.
For Investors and Strategic Allocators
The most durable value creation in this market is likely to come from businesses that combine credible hardware performance with software-enabled differentiation and strong service ecosystems. Investors should pay attention to product launch cadences that demonstrate alignment with high-growth use cases, as well as to the ability of incumbents and challengers to sustain margin discipline amid rising software expectations and supply chain sensitivity. Companies that can expand recurring value through software, support, and application bundles may offer more resilient growth profiles than those relying primarily on hardware replacement cycles.
For Procurement and Engineering Leaders
Buying decisions should increasingly reflect total measurement workflow value rather than headline specifications alone. Priorities may include waveform capture rates, analysis automation, multi-channel flexibility, portability where field use matters, and integration with existing design and quality systems. Procurement teams should also evaluate long-term supportability, calibration pathways, and the availability of application-specific guidance, particularly in regulated or high-stakes environments. For organizations operating across multiple sites or engineering contexts, instruments that support consistent workflows from bench to field can reduce training overhead and improve measurement continuity.
Closing Perspective
The oscilloscope market is moving from a specification-centric competition model toward a workflow- and analysis-centric one. Growth is being shaped by higher signal complexity, expanding compliance demands, and the need for measurement tools that fit into broader engineering environments rather than standing apart from them. The commercial opportunity lies in aligning product strategy with these realities: delivering high-performance capability where it matters, embedding intelligent analysis where it accelerates decisions, and offering flexible form factors where measurement must travel beyond the lab. For organizations seeking to navigate this landscape with greater precision, a deeper dive into segment-level demand patterns, regional procurement shifts, and competitive release roadmaps can provide the granularity needed to de-risk planning and prioritize the most valuable opportunities.
For detailed analysis of this topic, please visit the official page: Oscilloscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Rupture Disc Market: Why the 3.7% CAGR Trajectory Signals Strategic Shifts for 2026
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Rupture Disc Market
Navigating a Mature but Evolving Safety-Critical Segment
The global rupture disc market reflects the steady, requirement-driven nature of pressure relief equipment across process industries. Measured against a 2025 base year and projected through 2032, the market demonstrates a composite annual growth rate of 3.7%, expanding from an estimated 678.2 million USD in 2025 to 874.6 million USD by 2032. Historical movement between 2020 and 2025 shows moderate but consistent expansion, with revenue climbing from 597.5 million USD to 678.2 million USD over the period. This trajectory indicates a market where demand is anchored by regulatory requirements, operational safety mandates, and gradual capacity additions rather than volatile cyclical spikes.
When viewed across the historical window, the pattern underscores resilience. The 2020-2025 sequence moved through a brief contraction in 2021 before recovering through 2022 and 2023, then stabilizing near 646 million USD in 2024 before reaching the 2025 mark. The forecast horizon suggested a continued climb toward 722.27 million USD in 2026, 752.04 million USD in 2027, and 774.06 million USD in 2028, before a slight plateau near 773.96 million USD in 2029. Growth resumes afterwards, advancing to 796.12 million USD in 2030, 841.71 million USD in 2031, and 874.6 million USD in 2032. This shape implies that the segment will experience a transitional period around the late 2020s, likely shaped by order timing, replacement cycles, and the uneven rhythm of capital projects across regions.
Market concentration further clarifies the operating environment. The top three companies account for roughly 49.5% of revenue, while the top five reach about 65.2%. This distribution reflects a landscape where established manufacturers hold meaningful share through technical credibility, application-specific product lines, and long-standing customer relationships in process safety. At the same time, the space is not dominated by a single entity, leaving room for differentiation through specialization, service models, and regional execution.
Key Challenges and Inflection Points
The rupture disc market is entering a phase where growth is increasingly shaped by product suitability, qualification rigor, and the timing of end-use capital spending rather than by broad volume expansion alone. Several structural challenges stand out.
-
Qualification intensity and testing expectations are rising. Pressure relief components are increasingly expected to demonstrate traceable raw materials, lot-level qualification testing, and burst tolerance performance that exceeds baseline code requirements. Suppliers that cannot consistently document cycle life and performance consistency face greater friction in regulated and sanitary applications.
-
Demand timing is uneven across industries. While oil and gas, chemicals, and pharmaceuticals continue to anchor core demand, project pipelines differ by region and by budget cycle. Replacement activity can cushion downturns, but new installations often lag when capital expenditure decisions are delayed.
-
Segment differentiation is becoming a commercial necessity. The market spans metallic, graphite, and non-metallic rupture discs, each with distinct performance profiles for pressure relief, corrosion resistance, temperature exposure, and cleanability. Customers are selecting based on process conditions rather than commodity pricing, which pushes suppliers to align product design more closely with application-specific requirements.
These pressures create a market where success depends less on broad reach and more on technical fit, documentation reliability, and the ability to reduce installation or compliance friction for buyers.
Abrasive Disc Market
Core Drivers Shaping Market Direction
Technical Innovation and Application-Specific Engineering
Product development is increasingly oriented toward higher performance under demanding conditions and easier integration into complex systems. Recent moves to expand rupture disc families for larger sizes and high-performance overpressure protection show how manufacturers are targeting installations where pressure relief must be both reliable and scalable. Equally notable is the push toward assembly-based designs that simplify installation and improve process safety. Such products are not simply incremental variations; they reduce integration risk and support faster commissioning, which matters in environments where downtime is costly and safety validation is strict.
Innovation is also visible in how manufacturers are addressing material and performance requirements simultaneously. Metallic and graphite rupture discs are being positioned with emphasis on traceable sourcing and in-house lot qualification testing that surpasses standard code expectations for cycle life and burst tolerance. In high-compliance segments, this level of documentation is becoming part of the value proposition rather than a back-office requirement.
Regulatory and Standardization Pressure as a Demand Catalyst
Regulatory expectations and industry standards continue to reinforce demand for verified, repeatable pressure relief solutions. In pharmaceutical and biotechnology environments, sanitary rupture discs are expected to support traceability, cleanability, and sterilization, often aligned with recognized standards such as ASME BPE, USP Class VI, and 3A. In food and beverage processing, hygienic designs are expected to be compatible with cleaning-in-place and sterilization-in-place conditions while resisting vacuum exposure. These expectations push buyers toward products that can demonstrate compliance consistency across lots and operating conditions.
At the same time, certain materials are gaining traction because they align with specific process challenges. Graphite rupture discs, for example, are valued in some corrosive media applications due to temperature-independent material behavior and conformity expectations in regulated environments. This does not mean any single material dominates across all use cases; instead, it highlights that buyers are matching material properties to process environments more deliberately than in the past.
Demand-Side Shifts in Process Safety and Sanitary Applications
End-user demand is being shaped by a combination of operational safety priorities and the expanding requirements of hygienic processing. In chemical plants and oil and gas facilities, pressure relief remains a core function tied to equipment integrity and operational risk management. In pharmaceutical, biotechnology, and food-related applications, the emphasis shifts toward preventing contamination, enabling sterilization, and maintaining cleanliness without sacrificing overpressure protection.
This dual demand profile creates divergent purchase drivers. Process industries prioritize reliability, compatibility with harsh conditions, and long service life. Sanitary applications emphasize cleanability, compliance traceability, and compatibility with cleaning and sterilization routines. As a result, the same product category serves fundamentally different selection criteria depending on the end market, which diversifies the competitive battlefield.
Supply-Side and Cost Structure Considerations
Cost dynamics in this market are closely linked to material selection, manufacturing precision, and qualification overhead. Metallic rupture discs make up the largest portion of the revenue base, with graphite and non-metallic products forming substantial but smaller portions of the mix. This distribution matters because material choice affects not only performance but also sourcing complexity, testing requirements, and pricing strategy.
Suppliers that invest in raw material traceability and in-house testing may face higher operational burdens, but they also reduce the risk of qualification failures and customer rejections. Over time, this can translate into stronger repeat business in applications where documentation and consistency are decisive. Conversely, cost pressures may intensify where buyers treat rupture discs as interchangeable unless a supplier can clearly justify performance advantages or compliance benefits.
Competitive Positioning and Strategic Differentiation
The competitive landscape is defined by manufacturers that have built strong reputations around specific application strengths, product architectures, and compliance-oriented designs.
Some manufacturers have concentrated on sanitary and hygienic rupture disc solutions designed for pharmaceutical, biotech, food, and beverage environments. These offerings emphasize reverse-acting and forward-acting designs, compatibility with cleaning and sterilization processes, and adherence to recognized standards. The value proposition here is not simply pressure relief; it is repeatable cleanliness, sterilization readiness, and documentation that supports regulated operations.
Other manufacturers have broadened their footprint across chemical, pharmaceutical, extrusion, and food industries with both metallic and graphite products, often spanning reverse-acting, forward-acting, sanitary, and ultra-low or bi-directional applications. This type of positioning supports a strategy of cross-industry reach, where customers in multiple process environments can source from a single supplier with a wide performance envelope.
There are also manufacturers focused on engineered, high-precision rupture discs and pressure relief components for more demanding or specialized systems. In these cases, differentiation comes from precision manufacturing, custom engineering support, and the ability to integrate rupture discs into broader pressure relief solutions.
Geographically, the field also includes internationally based manufacturers serving industrial pressure relief applications with dedicated product series. These companies contribute to a market structure where regional execution, product line breadth, and technical support can be as important as headline brand recognition.
Recent Activity as a Window into Strategic Priorities
Recent product activity among leading manufacturers points to a clear strategic emphasis on performance range, installation efficiency, and line expansion. One notable direction has been the extension of established rupture disc lines into larger sizes to address higher-demand industrial applications. This suggests that manufacturers are responding to customers who need overpressure protection in more demanding configurations without abandoning proven design principles.
Another important move has been the launch of cartridge-based rupture disc assemblies intended to simplify installation and improve process safety. This reflects a broader shift toward reducing integration complexity, which is particularly valuable in facilities where maintenance access, replacement time, and installation accuracy directly affect operational continuity.
In parallel, the introduction of new rupture disc families for high-performance overpressure protection shows that suppliers are not relying on legacy portfolios alone. Instead, they are expanding into product sets designed to cover a wider performance spectrum, which can help capture demand from customers seeking a more consistent platform across multiple installations or process conditions.
Together, these developments indicate competition is increasingly being fought on the basis of application coverage, integration convenience, and validated performance rather than basic presence in the category.
Market Structure and Evolution Patterns
The current concentration pattern suggests a market that is consolidated enough to reward scale and technical credibility, yet open enough to allow differentiation by specialization. Companies with strong positions in sanitary or hygienic segments can outperform in regulated environments even if they are not the largest overall. Similarly, suppliers with broad material coverage and engineering support can build relevance across multiple industries by reducing the need for customers to manage several sources for different rupture disc types.
Looking ahead, the structure may evolve through a combination of selective consolidation and continued segmentation. Larger players may strengthen their position by broadening product lines or acquiring specialized capabilities, especially where compliance, testing, and documentation create high barriers to switching. At the same time, smaller or more specialized manufacturers can persist by serving niche performance requirements, regional demand, or application-specific customization that larger platforms do not prioritize.
For buyers, this environment often translates into a trade-off between simplified sourcing and best-fit performance. For suppliers, it means that competitive advantage is increasingly tied to how well a product platform aligns with customer qualification needs, installation constraints, and process conditions.
Future Outlook: Three Trends to Watch
Trend 1: Compliance and Documentation as Commercial Gateways
Over the next several years, traceability, qualification testing, and standards alignment are likely to become even more central to purchasing decisions, especially in pharmaceutical, biotech, food, and beverage applications. Buyers may increasingly treat documented consistency as a prerequisite rather than a bonus. This creates an opportunity for suppliers that already operate with rigorous raw material controls and lot-level testing, and a challenge for those that cannot match the same level of evidence when customers compare options.
The commercial implication is clear: in regulated segments, product performance and product documentation are becoming inseparable. Companies that can streamline qualification, reduce validation burden, and maintain consistent performance across lots are better positioned to secure long-term preference.
Trend 2: Platform-Based Product Strategies and Integration Convenience
A second trend is the move toward product families and assemblies that make selection, installation, and replacement more straightforward. Expanding line sizes and introducing cartridge-style designs are examples of how manufacturers are trying to reduce friction in the field. If this direction continues, buyers may value platform consistency across units and sites because it simplifies inventory planning, maintenance, and engineering review.
This trend opens commercial opportunities for suppliers that can offer a coherent range rather than isolated point products. It also raises the stakes for those whose portfolios are fragmented or difficult to standardize across applications.
Trend 3: Material Selection Becoming More Context-Specific
The market is unlikely to converge on a single material solution. Instead, metallic, graphite, and non-metallic rupture discs are expected to retain distinct roles based on pressure requirements, corrosion exposure, temperature conditions, and sanitary needs. The more important shift is that selection may become more deliberate, with buyers matching material characteristics to process environments rather than defaulting to a standard choice.
PW Consulting
This creates opportunity for manufacturers that can clearly articulate when and why a given material is appropriate, particularly in corrosive or temperature-sensitive services. It also suggests that sales and technical support will matter as much as the product itself, because the right choice often depends on operating conditions that differ from one installation to the next.
Risks and Uncertainties
Despite a generally constructive growth outlook, several uncertainties bear watching. Capital expenditure timing in oil and gas and chemical end markets can delay new installations and shift demand toward replacement cycles. Regulatory interpretations and customer qualification expectations can also evolve, changing the documentation or performance thresholds required for approval. Finally, raw material sourcing and manufacturing quality control remain sensitive points; any inconsistency in materials or testing can quickly affect customer confidence in safety-critical applications.
In addition, the late-2020s plateau visible in the forecast suggests that growth may not be linear. Periods of stabilization can emerge as project timing, replacement cycles, and regional demand patterns interact. Companies that rely too heavily on a single end-use sector or a narrow material set may feel those pauses more acutely than diversified competitors.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
-
Align product roadmaps with the applications where compliance documentation and performance consistency matter most. In sanitary and regulated environments, the ability to prove traceability and repeatable burst tolerance can be as influential as the headline design features.
-
Reduce installation and integration friction wherever possible. Cartridge assemblies, broader size ranges, and clearer platform consistency can make a product line easier to specify, deploy, and maintain, which strengthens customer preference over time.
-
Treat material strategy as application strategy. Rather than competing on a single material across all use cases, sharpen the message around where metallic, graphite, or non-metallic rupture discs are the best fit and support that claim with technical evidence.
For Investors and Strategic Planners
-
Focus on suppliers that combine application specialization with credible qualification practices. In a market where the top five companies hold a majority share, durable advantage often comes from segments where technical barriers and documentation requirements limit easy substitution.
-
Watch for platform expansion and consolidation signals. Product line broadening, assembly-based designs, and moves into larger-scale industrial protection can indicate where manufacturers are trying to capture more share per customer and reduce churn.
-
Consider how end-use timing affects revenue visibility. Because demand is influenced by project cycles in oil and gas, chemicals, and pharmaceuticals, diversification across applications and regions can reduce exposure to localized capital spending delays.
Rubber Diaphragm Market
For Procurement and Operations Leaders
-
Evaluate rupture disc suppliers on total qualification burden, not just unit price. In safety-critical or sanitary applications, consistency of documentation, testing evidence, and standards alignment can reduce risk and speed approval.
-
Standardize where possible, but preserve application fit. A coherent product platform across sites can simplify maintenance and inventory, but it should still be matched to pressure, temperature, corrosion, and cleanability requirements.
-
Request clear evidence of lot-level quality control and material traceability, especially where corrosive media, sterilization conditions, or stringent compliance expectations are involved. This helps ensure that the selected product performs consistently across installations.
Why Deeper Intelligence Matters Now
The rupture disc market is not undergoing a sudden disruption, but it is becoming more demanding in the ways that matter most to commercial decisions: qualification rigor, application fit, integration convenience, and documentation reliability. In that environment, general market awareness is useful, but segment-level clarity is what supports confident product planning, sourcing choices, and investment prioritization.
Detailed segmentation data, regional demand patterns, material and application splits, company-level positioning, and procurement-relevant benchmarks can sharpen these decisions considerably. For teams evaluating where to invest, which applications to prioritize, and how to compare suppliers beyond price, a more granular view of the market can help translate broad trends into actionable next steps. Readers seeking that level of detail can find it in the full PW Consulting report, which extends the analysis into deeper segmentation, competitive detail, and tailored decision frameworks.
For detailed analysis of this topic, please visit the official page: Rupture Disc Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Toilet Tank Fittings Market: Why Flush Valve Dominance & 7.5% CAGR Shift Next Decade
By PW Consulting, 2026-09-21
The Toilet Tank Fittings Market at an Inflection Point: Strategic Trends and Commercial Opportunities
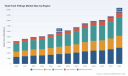
The toilet tank fittings market is undergoing a structural shift. What was once a commoditized segment of plumbing hardware is now shaped by tightening water efficiency mandates, rising material and energy costs, and evolving end-user expectations for reliability and water conservation. Between 2020 and 2025, the market expanded from approximately 4.2 billion USD to 5.9 billion USD, and the trajectory suggests continued growth through the early 2030s, with a compound annual growth rate of roughly 7.5 percent. By 2032, total revenue is projected to approach 9.7 billion USD. These figures point to a market that is scaling steadily, but the value creation is increasingly concentrated among players who can navigate regulation, supply chain volatility, and shifting application demand.
The growth story is not simply about volume. It reflects a re-pricing of performance, compliance, and serviceability. For executives, investors, and procurement leaders, the key question is no longer whether demand will expand, but where margins will be defended, which product architectures will win, and how quickly the competitive landscape will consolidate around differentiated capabilities.
Mapping the Current Market Landscape
The market today is characterized by a moderate level of concentration. The top three players account for about 55 percent of revenue, while the top five reach approximately 70 percent. This concentration indicates that scale, distribution breadth, and brand trust still matter, yet there is room for specialized entrants and regional winners to gain share through product fit, faster innovation cycles, or superior after-market support.
In terms of product architecture, flush valves and fill valves together form the core of the revenue base, with a residual share spread across complementary fittings and accessories. The application side remains anchored in residential demand, which continues to represent the largest share of volume, while hotels and commercial buildings contribute a meaningful but smaller portion of the total. Regionally, the market is broad-based, with significant footprints across North America, Europe, and Asia Pacific, alongside smaller but growing contributions from Latin America and the Middle East and Africa.
The strategic takeaway is that the market is large enough to support multiple winners, but not so fragmented that differentiation is optional. Leaders are already separating themselves through product availability, fit-for-purpose repair solutions, concealed system expertise, and supply chain reliability.
Core Challenges and Turning Points
Three challenges are reshaping how companies compete in this space.
- Regulatory stringency is raising the performance floor. Efficiency requirements are no longer isolated pilots. EPA WaterSense mandates high-performance, low-flow fittings in tank-type toilets with maximum full flush volumes of 1.6 gallons per flush, while California Title 20 standard requires tank-type dual-flush toilets manufactured on or after January 1, 2025 to limit full flush to 1.28 gallons per flush. These thresholds are compressing design freedom and rewarding manufacturers that can deliver consistent low-flow performance without sacrificing durability or user satisfaction.
- Input cost pressure is eroding the margin buffer. Recent pricing actions illustrate the sensitivity of the category to plastics and energy costs. Geberit implemented a 2 percent price increase on plastic piping and select products effective June 2026 to offset rising energy and plastics costs linked to geopolitical factors. This is not an isolated event; it signals that cost volatility is now a recurring theme, and companies that cannot pass through cost changes or redesign for material efficiency will face margin compression.
- Aftermarket and repair dynamics are becoming a strategic battleground. As original installations age and retrofit cycles accelerate, the ability to deliver universal repair kits, replacement flappers, fill valves, and flush components is increasingly important. A market that generates recurring demand from maintenance and replacement creates an opening for players with strong SKU coverage, clear compatibility mapping, and dependable availability.
Together, these forces are turning the market into a test of execution. Regulatory compliance is rewriting product specifications. Cost dynamics are exposing the limits of static pricing models. And the repair ecosystem is rewarding companies that can reduce friction for installers and homeowners alike.
Key Drivers Behind the Next Growth Cycle
Technology Innovation and Product Architecture
Innovation in toilet tank fittings is less about radical reinvention and more about precision engineering in service of water performance, durability, and ease of maintenance. Fill valves and flush valves are being refined to deliver reliable operation at lower flow rates, while minimizing noise, leakage, and installation complexity. The emphasis is shifting toward designs that maintain performance over a longer lifecycle, resist wear from frequent use, and simplify replacement in both new construction and retrofit scenarios.
Concealed tank systems are a notable example of where product architecture and installer preferences intersect. These systems can improve aesthetics and spatial efficiency in residential and commercial settings, but they also require informed replacement and service strategies. Players that publish updated parts and service documentation, and that maintain compatibility across common installations, gain an operational advantage. Geberit's release of a North America product and parts catalog in early 2026, focused on concealed tank systems and replacement flushing components, reflects the broader industry emphasis on making serviceable systems easier to specify and maintain.
From a strategic perspective, innovation that reduces total cost of ownership, improves fit across major toilet platforms, and aligns with efficiency mandates is more valuable than innovation that simply adds features. The winning designs are those that help customers meet compliance without introducing installation risk or user dissatisfaction.
Policy and Regulatory Environment
Regulation is now one of the strongest forces shaping product roadmaps and demand patterns. The EPA WaterSense framework and California Title 20 standard are not abstract guidelines; they directly influence what can be specified, purchased, and installed. As these requirements become embedded in procurement standards and building codes, manufacturers need to ensure that tank fittings and associated toilet systems meet flow thresholds consistently across product lines.
This regulatory environment has several implications. First, it rewards scale players and technically capable suppliers that can validate performance and provide assurance to specifiers and buyers. Second, it raises the importance of documentation, testing, and compatibility claims, especially where local authorities or large buyers require proof of compliance. Third, it can accelerate substitution toward designs that perform well at reduced flow rates, which may alter the relative attractiveness of different product segments over time.
Toilet Partitions Market
For commercial and hospitality end users, these regulations intersect with broader sustainability goals and operating cost pressures. Water efficiency is no longer just a compliance checkbox; it is an operating expense lever. That connection strengthens demand for fittings that deliver dependable low-flow performance and reduces the tolerance for products that fail to meet expectations over time.
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, behavior is changing in ways that favor reliability, water savings, and efficient maintenance. In residential settings, homeowners and remodelers increasingly look for repair solutions that are easy to install, broadly compatible, and unlikely to require repeated service calls. This is especially relevant in older housing stock where toilet systems may be a frequent source of maintenance issues. The appeal of universal repair kits and straightforward replacement components remains strong because they reduce uncertainty and labor cost.
In hospitality and commercial buildings, procurement decisions are increasingly influenced by lifecycle considerations. Facility operators want fittings and flushing systems that reduce complaint volumes, simplify maintenance, and support sustainability reporting. The result is a slower but higher-value demand pattern: fewer impulse purchases, more specification-driven buying, and greater scrutiny of total performance rather than upfront price alone. This environment tends to reward brands that can demonstrate consistency, availability, and clear compatibility across common installation types.
One important nuance is that demand is not uniform. Residential replacement activity can be highly cyclical and sensitive to housing turnover, renovation spending, and regional repair cultures. Commercial and hospitality demand, by contrast, is more tied to occupancy, renovation cycles, and operational budgets. Understanding these differences is essential when planning product mix, inventory, and channel strategy.
Supply Chain and Cost Structure Dynamics
Supply chain dynamics are exerting pressure on both cost and service levels. Plastics, energy, and logistics inputs have become more variable, and geopolitical factors can quickly translate into pricing adjustments or availability constraints. The recent 2 percent price increase on plastic piping and select products by Geberit in June 2026 is a concrete illustration of how cost pressures are being managed at the product level.
Pipe Fittings Market
This environment is reshaping competitive advantage in several ways. Companies that can design for material efficiency, standardize across platforms, and manage bill-of-materials complexity are better positioned to absorb cost shocks. Those with stronger supplier relationships, flexible manufacturing footprints, and disciplined inventory practices can also protect service levels when demand spikes or input availability tightens. Conversely, players that rely on rigid cost structures or narrow supplier bases may be forced into reactive pricing moves that affect competitiveness.
The broader implication is that cost leadership in this market is increasingly about control over design, sourcing, and serviceability, not just manufacturing scale. The ability to balance compliance, durability, and material cost will determine which companies protect margins as the market expands.
Competitive Landscape and Leading Strategies
Positioning of Key Players
The competitive field includes companies with distinct value propositions, distribution strengths, and product philosophies.
- Fluidmaster has built a strong association with universal toilet tank fill valves, flappers, and complete repair kits for residential and commercial use. Its positioning centers on compatibility and breadth of repair solutions, which aligns well with the aftermarket and replacement demand that sustains much of the category.
- Korky manufactures universal toilet tank repair kits and components, including fill valves, flush valves, and flappers made in the USA. The emphasis on domestically produced components can be a differentiating point in segments where supply origin, quality consistency, and local availability matter to distributors and end users.
- Danco provides toilet tank repair kits with fill valves, flappers, and hardware for universal application across brands. Its approach reinforces the broad-compatibility model, supporting installers and consumers who need reliable fixes across a wide range of existing toilet platforms.
- Geberit offers concealed tank systems, flushing mechanisms, and replacement parts for residential and commercial installations. Its positioning is more oriented toward engineered systems and specification-driven environments, where performance, service documentation, and parts availability are central to long-term value.
These profiles show two complementary routes to competitiveness. One is the universal repair and replacement model that focuses on compatibility, SKU coverage, and immediate serviceability. The other is the engineered systems model that emphasizes concealed architectures, specification support, and durable replacement ecosystems. Both can win, but they require different operational capabilities and different go-to-market approaches.
Strategic Differentiation in Practice
Leading players are differentiating along several dimensions that matter to buyers and installers.
PW Consulting
- Compatibility and coverage. Broad fit across major toilet brands reduces friction in the aftermarket and increases the likelihood that a repair kit or replacement part will be the right solution the first time.
- Service documentation and parts availability. Updated catalogs and clear replacement pathways help specifiers, distributors, and maintenance teams act quickly. This is particularly important for concealed systems and commercial applications where downtime carries a higher cost.
- Performance under regulation. Products that consistently meet low-flow requirements while maintaining durability create trust with water-conscious buyers and compliance-sensitive procurement teams.
- Pricing discipline in a volatile cost environment. The ability to adjust pricing transparently, manage input cost exposure, and preserve product value is becoming a competitive signal in its own right.
The market is not simply rewarding the lowest price. It is rewarding predictability: predictable performance, predictable availability, and predictable total cost. That is a meaningful shift for a category that has historically competed heavily on convenience and replacement fit.
How the Landscape Is Evolving
Several trends are shaping the evolution of the competitive field.
- Moderate consolidation pressure. With top players already holding a substantial share, larger platforms may seek to expand through brand portfolios, distribution reach, or targeted acquisitions that add compatibility breadth or geographic coverage. At the same time, the existence of strong niche positions suggests that consolidation will be selective rather than blanket.
- Differentiation by application. Residential replacement remains a volume engine, but commercial and hospitality applications can support higher-value specifications and longer-cycle relationships. Companies that can serve both segments well, without diluting focus, are likely to capture a more resilient revenue base.
- New entrants and specialized challengers. The market still allows room for challengers that focus on specific product weaknesses, underserved compatibility gaps, or regional service advantages. Success for new entrants will depend on solving a clear pain point rather than competing broadly from day one.
- Increasing importance of service ecosystems. As concealed systems and more complex flushing mechanisms become more common in certain segments, the value of replacement parts, installation guidance, and support documentation will rise. Companies that treat service as part of the product proposition will be better positioned over time.
The overall direction is toward a market where breadth, compliance, and service reliability matter as much as the core mechanical function of the fitting. That creates opportunities for firms that can connect product performance with practical installation and maintenance outcomes.
Forward Trends and Commercial Implications
Trend One: Compliance-Driven Product Design Will Become Table Stakes
Over the next three to five years, low-flow performance and regulatory alignment will move from competitive advantage to baseline expectation. As standards are adopted more broadly and buyer expectations rise, product lines that cannot reliably meet efficiency requirements will face declining relevance in many specification and replacement contexts. The commercial opportunity lies in designing for compliance without sacrificing durability or ease of service, and in communicating performance clearly to specifiers and buyers. The risk is that companies treat regulation as a checkbox rather than a design constraint, which can lead to inconsistency, complaints, and slower adoption in higher-value segments.
Trend Two: Material Cost Volatility Will Reward Design and Sourcing Discipline
Cost pressure from plastics, energy, and logistics is likely to remain a recurring theme rather than a temporary disruption. Companies that can reduce material intensity, standardize components, and manage supplier exposure will be better positioned to protect margins and maintain pricing credibility. There is also an opportunity in redesigning products to use materials more efficiently while preserving performance. The downside risk is reactive pricing that erodes trust or slows demand, especially in price-sensitive residential replacement segments.
Trend Three: Aftermarket and Serviceability Will Gain Relative Importance
As installations age and retrofit activity continues, the market's recurring replacement layer will remain strategically important. Product lines that make repair faster, reduce compatibility uncertainty, and support clear part identification will benefit from repeat demand and stronger channel relationships. This is particularly relevant where concealed systems and commercial installations create higher stakes for downtime and maintenance efficiency. The opportunity is to treat the aftermarket as a design input, not an afterthought. The risk is underinvesting in SKU availability, documentation, or compatibility mapping, which can weaken a otherwise strong product portfolio.
Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
- Prioritize product architectures that meet current efficiency mandates while preserving durability and user satisfaction, especially in flush and fill valve designs.
- Strengthen compatibility mapping and repair kit coverage to reduce installation friction and capture recurring replacement demand.
- Build pricing and sourcing strategies that can respond to input cost volatility without undermining channel trust or demand stability.
- Treat service documentation and parts availability as part of the product value proposition, particularly for concealed systems and commercial applications.
For Investors and Strategic Buyers
- Look for companies with strong aftermarket relevance, broad compatibility, and demonstrated ability to manage compliance and cost complexity.
- Assess exposure to regulatory-driven demand shifts, especially where efficiency standards are expanding beyond early-adopter regions.
- Evaluate supply chain resilience and material efficiency as indicators of margin defense, not just operational hygiene.
- Recognize that value creation may come from better service ecosystems and documentation as much as from core product innovation.
For Procurement and Specification Teams
- Focus on total performance and lifecycle reliability, not just upfront unit price, especially in commercial and hospitality contexts.
- Verify compliance with current efficiency requirements and confirm compatibility before specifying fittings or repair solutions at scale.
- Favor suppliers that can provide clear documentation, dependable availability, and predictable replacement pathways to reduce maintenance risk.
The strategic stakes in the toilet tank fittings market are rising. Growth is supported by a large and diversified demand base, but the value is being reallocated toward players who can align product performance with regulation, cost reality, and service expectations. For decision makers, the most valuable insight is that the market reward system is shifting from convenience alone to predictable performance across compliance, maintenance, and cost. Detailed segment-level data, regional dynamics, and company-specific assessments can sharpen these choices further, and a full research report can provide the granularity needed to translate these trends into product plans, investment theses, and procurement strategies.
For detailed analysis of this topic, please visit the official page: Toilet Tank Fittings Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vitamin E Market 2026: Why a 5.3% CAGR Propels Revenue to $3.32 Billion by 2032
By PW Consulting, 2026-09-21
Vitamin E Market Outlook 2026–2032: Strategic Trends and Commercial Opportunities
The vitamin E market is navigating a phase of measured expansion, supply-side recalibration, and evolving demand priorities across multiple end-use sectors. With a global market base of approximately USD 2.21 billion in 2025 and a projected compound annual growth rate of about 5.3 percent through 2032, the sector is expected to reach roughly USD 3.32 billion by the end of the forecast period. This trajectory reflects steady demand from nutraceuticals, animal nutrition, functional foods, and personal care, but it also masks underlying structural shifts that will determine which players capture disproportionate value in the coming years.
Several forces are reshaping competitive dynamics. Demand patterns are becoming more differentiated by geography and application, while sourcing, regulatory compliance, and formulation science are increasingly important differentiators. At the same time, capacity constraints, input volatility, and shifting labeling requirements are forcing companies to rethink procurement, product architecture, and commercial strategy. The following analysis outlines where the market stands today, what is driving change, how incumbents are positioning themselves, and where the most actionable opportunities lie for decision-makers over the next three to five years.
Market Snapshot: Growth Trajectory and Structural Challenges
A Market Expanding at a Moderate but Consistent Pace
The vitamin E market has grown from roughly USD 1.65 billion in 2020 to an estimated USD 2.21 billion in 2025, with forward projections pointing to a 2032 valuation near USD 3.32 billion. The implied 2026–2032 CAGR of about 5.3 percent reflects steady, rather than explosive, growth. This pace is consistent with a mature but still expanding category, where volume and price dynamics are influenced by both demand-side pull and supply-side friction.
Demand is broadly distributed across dietary supplements, animal nutrition, functional food and beverages, and cosmetics and other applications. The supplement segment remains the largest contributor to total demand, supported by consumer interest in immune health, antioxidant benefits, and aging-related nutrition. Animal nutrition continues to be an important volume driver, particularly in feed premixes and livestock health formulations. Functional foods and beverages, along with cosmetic applications, represent smaller but increasingly differentiated demand pools that reward higher-purity, naturally sourced, or specialized forms of vitamin E.
Regionally, the market is not uniform. Asia Pacific accounts for the largest absolute share of demand, reflecting scale in manufacturing, nutrition product formulation, and feed production. Europe and North America remain significant, with demand shaped by regulatory frameworks, premiumization trends, and specific labeling or sourcing requirements. Latin America and the Middle East/Africa contribute smaller shares but are noteworthy for localized growth dynamics and evolving formulation standards.
Three Structural Challenges Shaping the Near-Term Outlook
Despite the overall growth trajectory, the market faces several interrelated challenges that will influence pricing, availability, and competitive positioning.
Supply-tight conditions and origin diversification. Market intelligence from early 2026 indicates that vitamin E supply opened the period in a firm and supply-tight position, with constrained availability reported from both Chinese and non-Chinese origins. This tightness highlights the market’s sensitivity to capacity utilization, crop availability, and geopolitical or logistical disruptions. Companies that depend on a single sourcing corridor face heightened risk when availability narrows across multiple origins simultaneously.
Input cost volatility and raw material exposure. Vitamin E production remains closely linked to vegetable oil markets and related agricultural inputs. Seasonal variations, agricultural challenges, and geopolitical pressures contribute to production cost volatility, which can compress margins or force price adjustments downstream. In a market where pricing power varies by segment and customer type, cost volatility disproportionately affects producers and formulators with less flexible sourcing or limited ability to pass through price increases.
Regulatory and labeling complexity. Regulatory frameworks continue to shape product formulation and labeling practices, particularly in the dietary supplement and functional food segments. For example, the U.S. Food and Drug Administration has required manufacturers to use updated Nutrition Facts and Supplement Facts labels that list vitamin E in milligrams, with conversion rules from international units. While smaller manufacturers were given transition flexibility, the broader implication is clear: regulatory and labeling requirements add complexity to product development, compliance, and market access. This complexity favors companies with strong regulatory capabilities and standardized documentation, while raising the operational bar for smaller entrants.
Key Drivers Reshaping the Market
Technological Innovation and Formulation Capabilities
Innovation in vitamin E is increasingly less about basic product availability and more about differentiation through purity, stability, sourcing, and delivery format. High-purity grades, microencapsulated beadlets, and specialized excipient forms such as tocopherol polyethylene glycol succinate (TPGS) illustrate how formulation science is expanding the range of usable vitamin E applications. Microencapsulation, for instance, can improve stability and handling in food and nutraceutical matrices, while TPGS-based formats support solubility and bioavailability in pharmaceutical and supplement applications.
These technical capabilities matter commercially because they allow suppliers to serve higher-value use cases and create more defensible product positions. A supplier that can offer consistent particle size, reliable solubility, and documented efficacy claims is better positioned to support customer innovation in functional foods, premium supplements, and pharmaceutical-grade formulations. In practice, technical differentiation is becoming a key lever for pricing and customer stickiness, especially where end-products are marketed on quality, stability, or clean-label attributes.
Regulatory and Policy Environment
Regulation remains a defining force in how vitamin E is labeled, documented, and commercialized. Labeling changes that shift vitamin E disclosure from international units to milligrams are not just compliance exercises; they influence product positioning, consumer communication, and formulation decisions. Companies that navigate these changes effectively can reduce time-to-market friction and maintain clarity in consumer-facing claims.
Vitamin D Market
Beyond labeling, regulatory expectations around sourcing transparency, traceability, and quality documentation are increasingly relevant. Suppliers that can provide full traceability, consistent quality standards, and regulatory support are better positioned for markets where compliance is a gatekeeper to entry. This is especially true for natural, non-GMO, or food-grade product claims, where documentation and process control are central to customer confidence.
Demand-Side Shifts in Consumer and Business Behavior
On the demand side, several behavioral shifts are reshaping where and how vitamin E is used. In dietary supplements, consumers continue to seek antioxidant and immune-support benefits, but they are also paying more attention to ingredient origin, clean-label positioning, and perceived naturalness. This has elevated the relative appeal of natural vitamin E in certain premium segments, even as synthetic forms remain important where cost-efficiency and functional performance are the priority.
In animal nutrition, demand is tied to livestock productivity, feed efficiency, and health management strategies. Vitamin E’s role in oxidation prevention and animal health supports its continued use in feed premixes, but the segment is also sensitive to overall agricultural cycles, feed cost pressures, and regional production patterns.
Meanwhile, functional food and beverage applications are expanding where manufacturers can integrate vitamin E into delivery formats that preserve stability and sensory quality. Cosmetics and personal care applications similarly depend on formulation compatibility and perceived efficacy. Across these demand pools, the common thread is that customers increasingly select vitamin E not only for its nutritional function but also for how well it fits into the broader product architecture and brand story.
Supply Chain and Cost Structure Dynamics
Supply chain resilience is now a central strategic issue. Raw material volatility, seasonal crop dynamics, and geopolitical factors can affect both availability and pricing. In a market that is already supply-tight at times, the ability to manage sourcing risk becomes a competitive advantage. Companies with diversified origin exposure, flexible contract structures, and vertically integrated or closely coordinated supply chains are better equipped to maintain continuity of supply and manage margin pressure.
PW Consulting
At the same time, procurement practices are evolving. Digital procurement tools, more transparent ordering platforms, and improved supply chain visibility can reduce friction in ingredient purchasing. For example, new e-commerce and digital procurement initiatives in the ingredients sector are easing sourcing for U.S. buyers and signaling a broader shift toward more efficient, data-informed purchasing. This trend matters for vitamin E because it can improve accessibility, shorten procurement cycles, and increase price transparency across smaller and mid-sized buyers.
Competitive Landscape: Strategic Positioning and Market Evolution
Differentiating Strengths Among Core Players
The competitive landscape includes a mix of large, globally diversified suppliers and more specialized producers. Several strategic patterns stand out.
Natural-source differentiation. Companies with strong positions in natural vitamin E and mixed tocopherols are leveraging plant-based sourcing, clean-label compliance, and brand recognition to serve dietary supplement, functional food, and nutraceutical customers. For some of these players, natural sourcing is not just a product attribute but a broader positioning platform tied to efficacy, traceable origin, and consumer-friendly formulation narratives.
Scale, purity, and format breadth. Other major suppliers emphasize high-purity vitamin E across oil and powder formats, broad formulation support, and reliable production capability. Microencapsulated beadlets and backward-integrated production are examples of how scale suppliers create consistency and reliability for customers who need stable supply and standardized quality across large volumes.
Specialized sourcing and regulatory depth. One notable strategic position is held by a supplier that produces natural, non-GMO vitamin E from sunflower oil with patent-protected manufacturing and full traceability. This kind of positioning is especially valuable in markets where origin, non-GMO status, and regulatory documentation are critical purchase criteria. The ability to provide concentrated natural vitamin E with documented process control creates a defensible niche even in a market with multiple global players.
Pharmaceutical and excipient-focused capabilities. Some participants compete by focusing on pharmaceutical-grade vitamin E, specialized excipients, and GMP-certified manufacturing. This positions them closer to drug delivery and supplement formulation markets where quality standards, solubility support, and regulatory expertise matter more than pure commodity volume.
Geographic and application diversification. Producers in China and broader Asia, as well as processors linked to palm and other vegetable oil supply chains, add scale and optionality to the market. Their relevance often depends on the balance between synthetic and natural product lines, application focus, and ability to serve both food/feed and nutraceutical segments. Where integrated production and expanding capacity align with demand growth, these players can strengthen their role in global supply.
How the Competitive Field Is Evolving
The market is not consolidating into a single dominant structure. Instead, it is evolving along multiple axes. On one hand, scale players continue to invest in production reliability, format breadth, and formulation support to defend their position in high-volume segments. On the other hand, specialized suppliers are carving out defensible niches based on natural sourcing, non-GMO positioning, pharmaceutical-grade quality, or application-specific functionality.
A useful way to think about the landscape is that it is both consolidating and fragmenting at the same time. Consolidation pressure exists where customers seek consistent global supply, documented quality, and strong regulatory support. Fragmentation persists where specialized product attributes, regional sourcing preferences, and application-specific formulation needs create room for differentiated suppliers. This combination means that competitive advantage increasingly depends on matching the right product architecture to the right customer segment rather than simply competing on volume alone.
New entrants and platform-based procurement models also matter. Digital procurement and ingredient marketplaces can lower barriers for smaller buyers and increase visibility across suppliers. At the same time, they can intensify price comparability and shift some bargaining power toward buyers who can quickly evaluate multiple sourcing options. Suppliers that can combine reliability, documentation, and technical service with competitive pricing are better placed to retain customer relationships in this environment.
Outlook for 2026–2032: Emerging Trends and Commercial Implications
Trend 1: Continued Tightness in Supply and Greater Emphasis on Sourcing Strategy
Given the supply-tight positioning observed in early 2026, it is likely that availability and price stability will remain sensitive to crop outcomes, capacity utilization, and geopolitical or logistical disruptions over the next few years. This does not necessarily imply persistent shortages, but it does suggest that sourcing strategy will be a recurring strategic issue.
For commercial players, the implication is clear: supply resilience should be treated as a core capability rather than an operational afterthought. Companies that diversify origin exposure, maintain strategic inventory buffers where appropriate, and strengthen supplier relationships across multiple geographies will be better positioned to manage volatility. For buyers, this trend reinforces the value of long-term agreements, qualified alternative sources, and clear specifications that reduce the risk of reformulation disruption when availability tightens.
Trend 2: Growing Premiumization and Natural-Source Relevance in Selected Segments
Demand for natural vitamin E and mixed tocopherols is likely to remain especially relevant in dietary supplements and certain functional food and personal care applications, where ingredient origin and clean-label narratives carry commercial weight. Natural-source positioning will not replace synthetic vitamin E across all applications, but it will continue to command strategic importance in segments where brand positioning, consumer perception, and regulatory documentation support a premium.
This trend creates opportunities for suppliers that can deliver consistent natural-source quality, clear traceability, and strong formulation support. It also creates opportunities for brands that can align vitamin E sourcing with broader product claims around naturalness, transparency, and efficacy. At the same time, premiumization can increase sensitivity to raw material costs, so margin management and sourcing efficiency remain important even in higher-value segments.
Trend 3: Formulation Science and Specialized Applications as Growth Multipliers
A second important trend is the growing role of specialized formats and application-aligned product design. Microencapsulation, solubility-enhancing excipients, and pharmaceutical-grade quality standards are expanding the set of commercially viable vitamin E applications. These formats can support better stability, easier handling, and stronger efficacy storytelling, which in turn enable product innovation in supplements, functional foods, and pharmaceutical-adjacent markets.
For companies looking to capture growth, this trend suggests that product leadership will increasingly come from solving formulation and performance problems, not just supplying bulk ingredient volume. Suppliers and formulators that invest in application expertise, stability data, and customer co-development can create stronger commercial positions than those competing primarily on price in undifferentiated segments.
Risks and Uncertainties to Monitor
Several uncertainties could influence how these trends play out. Continued raw material volatility could pressure margins, particularly for producers with limited cost flexibility. Regulatory changes, including evolving labeling or documentation requirements, could increase compliance burdens and favor better-resourced players. Supply disruptions affecting either Chinese or non-Chinese origins could create periodic tightness that reshapes pricing and availability. In addition, competitive pressure from digital procurement and greater price transparency could compress margins in segments where differentiation is weaker.
A further uncertainty is demand responsiveness. If economic conditions or consumer spending patterns shift, discretionary supplement and premium functional food categories could experience slower growth, while animal nutrition and more essential feed applications may prove more stable. Companies should therefore avoid assuming uniform growth across applications and regions.
Strategic Recommendations for Decision-Makers
For Manufacturers and Ingredient Suppliers
First, invest in application-level differentiation rather than competing solely on volume and price. Formulators and suppliers can strengthen commercial positioning by expanding capabilities in high-purity grades, stabilized formats, and specialty excipients that solve specific customer problems. Technical service, stability performance, and regulatory support are increasingly part of the value proposition.
Second, build a sourcing strategy that reduces single-point dependency. Diversifying origin options, qualifying alternative suppliers, and maintaining flexible contract structures can help manage the risk of supply-tight periods. Where natural-source or non-GMO positioning is strategically important, ensure that traceability and documentation are robust enough to support customer claims and regulatory requirements.
Third, use formulation and stability expertise as a customer retention tool. In categories where product consistency and shelf life matter, suppliers that can help customers optimize performance in the final formulation are more likely to secure repeat business and co-development relationships.
Synthetic Vitamin E Market
For Investors
The vitamin E market offers a mix of steady demand and periodic supply volatility, which means that investment theses should account for both structural growth and operational resilience. Favorable exposure may be found in suppliers with diversified application portfolios, strong format breadth, and credible natural-source or pharmaceutical-grade positions. Companies with vertically integrated production, traceability capability, and demonstrated ability to manage raw material volatility are better positioned to defend margins through cycles.
Investors should also pay attention to where premiumization and formulation complexity are expanding value pools. Segments that reward specialized performance, documentation, and clean-label positioning may offer stronger differentiation than high-volume commodity-style segments. At the same time, due diligence should include sensitivity to input cost volatility, regulatory shifts, and the impact of digital procurement on pricing dynamics.
For Procurement and Commercial Teams
Procurement teams should treat vitamin E sourcing as a strategic risk-management function, not just a price-shopping exercise. Evaluating suppliers on the basis of origin diversity, quality documentation, supply reliability, and application support can reduce disruption risk and improve long-term outcomes. Where possible, dual or multi-origin qualification can provide a buffer when one supply corridor becomes constrained.
Commercial teams should also monitor how regulatory and labeling requirements affect customer needs. Clear documentation, consistent unit disclosure, and formulation alignment can reduce compliance friction for customers and strengthen supplier relationships. In practice, the more a supplier can help customers navigate labeling, quality, and formulation challenges, the more defensible its position becomes.
Conclusion
The vitamin E market is set to expand at a moderate pace through 2032, but the real strategic story lies in how supply resilience, regulatory complexity, formulation innovation, and demand-side premiumization interact. The sector is not defined by a single dominant theme; rather, it rewards participants that can align product capabilities with specific customer needs while managing the operational risks embedded in raw material volatility and supply tightness.
For manufacturers, the opportunity is to move up the value curve through format specialization, traceability, and application support. For investors, the opportunity lies in identifying players with resilient supply positions and credible differentiation in natural-source, pharmaceutical-grade, or application-specific segments. For procurement and commercial teams, the priority is to treat sourcing as a strategic capability that reduces disruption risk and improves long-term supplier alignment.
Given the range of interrelated factors shaping this market, decision-makers will benefit from more granular visibility into regional demand dynamics, application-level growth patterns, pricing behavior, and supplier-specific capability profiles. Detailed segmentation data and customized strategic assessment can help translate these market-level trends into company-specific action plans. For teams seeking a deeper, more targeted view of the vitamin E competitive landscape and forward opportunities, the full research report provides the additional detail needed to support planning, sourcing, and investment decisions.
For detailed analysis of this topic, please visit the official page: Vitamin E Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fuel Cell Electric Vehicles Market: Decoding 26.6% CAGR Growth Trajectory to 2032
By PW Consulting, 2026-09-21
Strategic Horizons: Navigating Commercial Opportunities in the Fuel Cell Electric Vehicle Market
The fuel cell electric vehicle (FCEV) sector is entering a phase of accelerated expansion, driven by technological maturation and targeted policy support. Market valuation in the base year of 2025 reached 7.08 million USD, reflecting a compound annualized growth rate of 26.6 percent across the forecast horizon extending to 2032. This growth trajectory marks a decisive shift from early-niche adoption toward broader commercial deployment, with revenue projections scaling toward 37 million USD by the end of the decade. While passenger segments continue to refine hydrogen integration for range and efficiency, heavy-duty and logistics applications are increasingly anchoring demand, creating asymmetric opportunities across vehicle classes and operational profiles.
PW Consulting Automotive & Machinery Research Center
Defining the Competitive Arena
Market structure currently reflects moderate concentration, with the top three participants capturing roughly 48 percent of total activity and the leading five firms accounting for approximately 52 percent. This distribution suggests room for specialized entrants and regional specialists, particularly where localized infrastructure development or vertical integration creates defensible positions. Leadership is increasingly defined not by aggregate volume but by the ability to align fuel cell architecture, hydrogen sourcing, and operational economics around specific use cases. Companies that treat the stack as a modular component rather than a proprietary black box are gaining flexibility in scaling across passenger, commercial, and stationary applications.
Critical Inflection Points
Three structural challenges are reshaping how stakeholders should evaluate opportunity and risk in this space. The first concerns the pace of refueling network expansion relative to vehicle rollout. Without coordinated station development, adoption patterns risk becoming fragmented, limiting total addressable demand even as vehicle supply improves. The second challenge sits in cost parity, particularly for fuel cell stacks, balance-of-plant systems, and hydrogen procurement contracts. Progress is visible, but sustained reductions depend on manufacturing scale, material innovation, and standardized maintenance models that lower lifetime operating expenses. The third challenge relates to demand-side framing: buyers are weighing total cost of ownership, uptime reliability, and regulatory compliance rather than technology credentials alone, meaning that value propositions must be expressed in operational terms rather than technical specifications.
Key Drivers Reshaping the FCEV Opportunity Set
Technology Pathways and Performance Gains
Advances in stack durability, power density, and cold-start behavior are expanding the practical operating envelope for hydrogen vehicles. Integrated designs that pair fuel cells with buffer batteries are improving transient response and enabling short zero-emission electric ranges, which is particularly valuable for urban delivery, off-road cycles, and environments with access restrictions. These architectures also reduce the burden on hydrogen fueling during stop-start duty cycles, helping operators manage downtime and energy costs.
Recent product activity illustrates how manufacturers are translating these gains into customer-facing value. Honda began customer leasing of the 2025 CR-V e:FCEV through select California dealerships, combining a domestically produced fuel cell module with plug-in battery capability that delivers up to 29 miles of electric range alongside hydrogen refueling. This approach positions the vehicle as a flexible tool for fleets that need both emissions performance and operational resilience. Hyundai reinforced its passenger lineage by debuting an all-new NEXO at the 2025 Japan Mobility Show, previewing a production model that builds on more than two decades of fuel cell development. Meanwhile, BMW has signaled a series-production timeline targeted for 2028, indicating growing confidence in scaling fuel cell platforms beyond demonstration fleets.
Policy Architecture and Regulatory Tailwinds
Regulatory frameworks are increasingly used to channel investment toward specific decarbonization outcomes rather than blanket technology support. In California, the Air Resources Board's 2025 annual evaluation reported 14,128 FCEVs registered as of April 2025, alongside a first recorded year-over-year decline of 291 units. This inflection underscores the sector's transition from early growth momentum to a more measured phase where infrastructure readiness, vehicle availability, and buyer economics must align. At the same time, the evaluation projects a network of up to 112 stations capable of supporting as many as 16,210 FCEVs by 2028, framing the policy task as one of synchronized build-out rather than unconstrained expansion.
Broader industry coordination is reinforcing this direction. The 2025 Hydrogen and Fuel Cell Seminar highlighted commercialization strategies and latest FCEV products, with a notable emphasis on heavy-duty applications where emissions intensity and duty cycles make hydrogen particularly relevant. Policy alignment with decarbonization targets is encouraging fleet operators and equipment manufacturers to experiment with hydrogen in segments where battery-only configurations face practical constraints. The implication for decision-makers is that incentives and mandates are becoming more targeted, and success will depend on matching vehicle deployment to the specific regulatory and operational context of each market.
Demand-Side Behavior and Fleet Economics
Buyers are increasingly evaluating FCEVs through the lens of operational continuity, refueling time, payload capability, and total cost of ownership. In commercial settings, hydrogen's appeal lies in its ability to support long ranges and rapid replenishment without the charging downtime associated with battery-only vehicles, which is especially relevant for heavy-duty trucking, regional logistics, and high-utilization routes. Passenger buyers are weighing similar trade-offs, though their decisions are more sensitive to fuel availability, residual value, and the perceived convenience of the energy pathway. This divergence means that demand creation is uneven: some segments require infrastructure confidence before volume scales, while others can move faster where refueling access and fleet incentives are already in place.
Electric Vehicles and Fuel Cell Vehicles Market
Supply Chain and Cost Dynamics
Cost structures are evolving through a combination of manufacturing scale, component standardization, and hydrogen supply contracts. As fuel cell stacks and related subsystems move from bespoke engineering toward repeatable production, the economics of per-unit cost and service intervals improve. Hydrogen supply is equally important: long-term sourcing agreements, on-site generation where feasible, and logistics optimization can materially affect operating expenses. Companies that vertically coordinate stack production, vehicle integration, and fuel supply are better positioned to manage variability in input costs and to offer predictable service arrangements. Conversely, reliance on fragmented supply chains can expose operators to price swings and availability risk, particularly in early-adopter regions where demand spikes may outpace supply flexibility.
Competitive Landscape and Strategic Positioning
Differentiation Strategies Among Leading Players
Leadership in this market is increasingly articulated through platform strategy, application focus, and ecosystem partnerships rather than headline vehicle counts. Toyota continues to advance its Mirai passenger FCEV, emphasizing integrated hydrogen fuel cell technology and a refined passenger experience. The company's positioning reflects confidence in hydrogen for segments where range, refueling speed, and technology credibility matter, even as it navigates the realities of limited refueling access in some markets. Hyundai has expanded its footprint across both passenger and commercial domains, with the Xcient heavy-duty FCEV and the Nexo passenger vehicle illustrating a dual-track strategy that targets high-utilization commercial demand alongside consumer adoption. This breadth allows Hyundai to apply learning from one segment to another, particularly where stack durability and operational data can be cross-leveraged.
Honda has adopted a modular and flexible approach by combining a U.S.-made fuel cell module with plug-in battery capability in the CR-V e:FCEV, supporting both hydrogen refueling and short electric range. This dual-energy configuration broadens the vehicle's usability and reduces dependence on any single refueling event, which is attractive for early adopters in areas where hydrogen availability is still developing. BMW's focus on series production targeted for 2028 signals an emphasis on manufacturing discipline and product readiness, suggesting a strategy built around scalable architecture rather than limited demonstration runs. Collectively, these positions point to a market in which differentiation is increasingly about how well a company integrates technology, supply, and customer use cases.
Market Evolution and Consolidation Dynamics
The competitive field is likely to evolve through a mix of consolidation, specialization, and selective entry. Established automakers are strengthening their positions through platform investments and product cadence, while component suppliers and hydrogen-focused companies are exploring opportunities to enter at the system, fueling, or service layer. In commercial applications, there is growing potential for partnerships that bundle vehicles, hydrogen supply, and maintenance into integrated offerings, reducing friction for fleet buyers and improving lifetime economics. At the same time, regional disparities in infrastructure and policy create natural fragmentation, where local champions may emerge around specific corridors, ports, or logistics hubs. The result is a landscape where broad scale and localized execution both matter, and where successful players will need to manage multiple business models simultaneously.
Recent events reinforce this multi-speed environment. California's latest evaluation highlights both the maturity of the current registration base and the urgency of expanding the station network to sustain further growth. The FCEV seminar circuit continues to serve as a venue for sharing commercialization strategies and product developments, indicating that the industry is moving from concept discussion to deployment detail. As these dynamics mature, companies that can align product timing with infrastructure milestones and customer readiness will gain an advantage over those that rely solely on technology leadership without considering the operating environment.
Forward Outlook: Trends and Risk Factors for 2026-2030
Trend One: Application-Led Growth in Commercial Heavy-Duty Segments
Heavy-duty and commercial applications are expected to play an outsized role in shaping demand over the next several years. The operational characteristics of long-haul routes, port operations, and high-utilization delivery cycles make refueling time, payload retention, and range reliability especially valuable, which aligns well with hydrogen's strengths. This trend suggests that commercial segments will not only drive volume but also provide the utilization data and service models needed to lower costs and refine stack design. For businesses, the opportunity lies in identifying routes and duty cycles where hydrogen offers a clear total-cost advantage and in structuring supply and maintenance arrangements that reduce operational uncertainty.
Trend Two: Infrastructure Synchronization as a Growth Determinant
Vehicle availability will increasingly need to be matched with station expansion and hydrogen supply reliability. As deployment scales, operators and buyers will scrutinize station uptime, geographic coverage, and pricing consistency, since these factors directly affect fleet planning and consumer confidence. Regions that coordinate station planning with vehicle rollouts and fleet incentives are likely to see faster adoption and more stable economics, while areas where supply and demand develop unevenly may experience slower momentum. This trend elevates the strategic importance of partnerships between vehicle manufacturers, fuel suppliers, and infrastructure developers, as well as the value of standardized operating practices that improve reliability across sites.
Trend Three: Modular Architectures and Dual-Energy Configurations
The integration of fuel cells with buffer batteries and plug-in capability is likely to become more common, offering flexibility in how energy is used across different driving conditions. Such architectures can improve transient performance, support short electric-only operation, and reduce dependence on frequent hydrogen refueling in mixed-use scenarios. This trend also opens the door to more adaptable business models, where vehicles can be configured for specific routes or customer preferences without sacrificing core fuel cell performance. The trade-off is complexity in design and service, so the winners will be those who manage modularity without compromising durability or maintenance simplicity.
Risk Considerations
Several uncertainties could shape the pace and distribution of growth. Infrastructure expansion may lag vehicle availability in some markets, constraining demand even where technology and policy support are strong. Hydrogen pricing and supply reliability remain sensitive to production methods, transport logistics, and contract structures, which can affect operating economics for both fleets and individual buyers. Policy environments may also shift as jurisdictions refine incentives and compliance mechanisms, creating variability in the timing and scale of demand. Finally, competition from battery-electric alternatives in chosen segments could pressure hydrogen's role in passenger applications, making it more important to anchor the value proposition in use cases where hydrogen offers clear differentiation.
Actionable Strategic Recommendations for Decision-Makers
For Vehicle Manufacturers and System Suppliers
Align product planning with the rhythms of infrastructure development and fleet readiness rather than pursuing volume in isolation. Prioritize applications where refueling time, range, and uptime translate into measurable operational advantages, and use those deployments to gather durability data and refine service models. Consider modular or dual-energy architectures that broaden customer appeal in early-adopter markets while preserving a clear core fuel cell value proposition. Build partnerships that connect stack production, vehicle integration, and hydrogen supply, since coordinated offerings can improve economics and reduce buyer friction. Monitor regions where station networks and policy frameworks are converging, and stage product introductions to coincide with practical refueling access rather than projected but unverified capacity.
Hydrogen Vehicle Market
For Investors and Capital Allocators
Evaluate exposure across the value chain with a focus on segments where utilization and total cost of ownership most favor hydrogen. Commercial heavy-duty applications, regional logistics corridors, and integrated fuel-and-service models present opportunities where operating economics can be validated more quickly than in broad passenger markets. Assess companies on the strength of their supply agreements, manufacturing scalability, and ability to manage service intervals, since these factors increasingly determine margin stability and customer retention. Be attentive to policy timing and infrastructure milestones, because demand in early markets can be highly sensitive to station availability and incentive structures. Diversify across complementary positions, including component suppliers, fuel logistics providers, and application-focused integrators, to capture value from different layers of the ecosystem.
For Fleet Operators and Procurement Leaders
Structure procurement around operational confidence and total cost rather than vehicle specifications alone. Prioritize routes and duty cycles where hydrogen's refueling speed, range, and payload characteristics deliver measurable benefits, and pilot deployments in areas with reliable fueling access. Negotiate long-term hydrogen supply terms and service arrangements that reduce variability in operating expenses and downtime. Use early deployments to collect data on fuel consumption, maintenance needs, and vehicle availability, then feed those insights into broader fleet planning. Where feasible, coordinate with multiple stakeholders to strengthen local station coverage and supply reliability, since improved infrastructure benefits not only a single fleet but the entire demand environment.
The Value of Targeted Intelligence
Success in this market depends on reading the interaction between technology, policy, infrastructure, and buyer economics in real time. Broad trends provide direction, but the details that matter most—station rollout timing, supply contract structures, stack durability outcomes, and application-specific economics—require focused analysis. Decision-makers benefit from access to segmented data and scenario-based guidance that connects market movement to operational choices, whether that means sizing a commercial pilot, sequencing product launches, or evaluating where capital will be most efficiently deployed. As the landscape continues to evolve, timely and granular intelligence becomes a practical tool for reducing uncertainty and improving execution.
For detailed analysis of this topic, please visit the official page: Fuel Cell Electric Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Stabilizer Bar Market 2032 Outlook: How 5.3% CAGR and Asia Pacific Demand Are Reshaping Competition
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Automotive Stabilizer Bar Market
The global automotive stabilizer bar market has demonstrated sustained expansion over the past half-decade, transitioning from a mature commodity component space into a strategically sensitive segment where weight, durability, and active damping performance directly influence vehicle platform competitiveness. Revenue crossed the $3.6 billion threshold in 2025 and is projected to reach $5.2 billion by 2032, reflecting a compound annual growth rate of 5.3 percent. The trajectory is not a straight line; it is shaped by platform electrification, tightening safety and emissions standards, raw material volatility, and a fragmented yet consolidating supplier landscape. For executives and investors, the market is no longer about volume alone. It is about aligning product architecture, sourcing strategy, and regional manufacturing footprint with where vehicle architectures are heading.
The growth profile shows a steady climb through 2025, followed by a noticeable inflection after 2028 as electrification and lightweighting programs mature across multiple vehicle segments. A brief plateau in 2030 hints at pricing pressure, platform transitions, or regional demand normalization, before acceleration resumes through 2032. This pattern underscores a market that is cyclical but structurally expanding, where short-term turbulence masks long-term demand shifts tied to vehicle mix and regulatory endpoints.
Market Status and Core Challenges
The stabilizer bar market today operates at the intersection of cost discipline and performance differentiation. Suppliers compete on material grade, hollow versus solid architecture, surface treatments, and integration with active or semi-active damping systems. The component itself is well understood, yet the value pool is shifting toward engineered variants that help OEMs meet stricter rollover and handling targets without adding mass or sacrificing durability.
Three challenges define the current turning point. First, the transition to electric vehicle platforms is changing suspension loading patterns and component packaging constraints. Battery weight alters roll dynamics, which increases the importance of stabilizer bar geometry, material selection, and joint design, but it also compresses available packaging space and introduces new durability targets for continuous high-torque scenarios. Second, raw material exposure remains a persistent margin risk. Steel stabilizer links and related components continue to hold a dominant share of the material mix at 72.1 percent in 2025, reflecting mature manufacturing processes and broad applicability. At the same time, aluminum-based solutions are gaining traction in lightweight programs, yet aluminum prices fluctuate 15 to 25 percent annually based on global supply-demand dynamics and geopolitical factors affecting mining and refining operations. This volatility complicates multi-year sourcing agreements and pressures cost planning for both solid and hollow designs.
Third, regulatory pressure is rewriting component priorities. European Euro 7 regulations drive continuous suspension system innovation, including lightweight and smart stabilizer link designs, while EU emissions regulations targeting 93.5 g CO2/km average fleet emissions by 2025 accelerate the adoption of lightweight suspension components. The result is not a regulatory burden in isolation; it is a design constraint that rewards suppliers capable of delivering weight reduction without compromising NVH, corrosion resistance, or fatigue life. Companies unable to engineer around these constraints face margin compression or displacement by more adaptive competitors.
Key Drivers of Market Change
The market is being reshaped by four interconnected drivers: technology innovation, regulatory direction, demand-side behavior, and supply chain cost structures. Each driver influences not just volume, but where margin and differentiation are created.
Technology innovation is moving the segment beyond generic passive bars. Active damping variants, hollow architectures for weight savings, and high-strength steel or aluminum grades are becoming standard expectations for premium and performance platforms. Recent product activity illustrates this shift. In March 2025, thyssenkrupp Automotive Technology launched a new high-strength aluminum stabilizer bar series designed specifically for electric vehicles, signaling a direct response to the weight and packaging demands of electrified powertrains. In April 2025, Federal-Mogul LLC introduced a new line of corrosion-resistant stabilizer bars with advanced surface treatment for harsh climates, addressing durability concerns in markets where road salt, humidity, and extreme temperatures shorten service life. These launches show that value is shifting toward application-specific engineering rather than commodity production.
Stabilizer Bars Market
Policy and regulation amplify the need for engineered solutions. Euro 7 and fleet CO2 targets are not one-time compliance events; they are continuous pressure points that encourage lightweighting, smarter link designs, and improved suspension tuning to reduce emissions indirectly through weight savings and efficiency gains. In practical terms, regulations reward designs that lower unsprung mass, improve handling without additional energy consumption, and extend component life to reduce replacement frequency. Suppliers that align their roadmaps with these requirements can position themselves as enablers of compliance rather than victims of it.
On the demand side, consumer and fleet behavior is bifurcating. Passenger vehicles continue to represent the larger share of demand, but commercial vehicles remain strategically important because stabilizer durability, corrosion resistance, and load capacity matter more heavily in sustained-duty applications. The broader trend is that automakers are increasing model variant complexity while tightening platform commonality, which means stabilizer bar programs must be flexible enough to serve multiple derivatives without incurring redundant tooling costs. Meanwhile, performance-oriented buyers and aftermarket channels continue to reward reinforced or specialized bars, creating parallel demand streams that do not always track OEM cycles.
Supply chain and cost structure changes are the fourth driver. The combination of steel’s continued dominance and aluminum’s price volatility creates a strategic sourcing dilemma: lean into mature steel processes for reliability and cost predictability, or move toward aluminum and hybrid designs for weight and performance at the risk of exposure to price swings. The answer increasingly depends on region, vehicle segment, and program volume. Geopolitical factors affecting mining and refining operations add another layer of uncertainty, making dual sourcing, localized production, and inventory buffers more relevant for long-cycle programs.
Competition Dynamics and Leader Strategies
The competitive field is moderately concentrated, with the top three firms holding roughly 32.5 percent and the top five holding 45.2 percent of the market. This concentration suggests a landscape where scale and regional presence matter, but specialization and application expertise can still create defensible niches. The leading players are not merely selling bars and links; they are competing on integration capability, material engineering, and proximity to OEM development cycles.
ZF Friedrichshafen AG stands out for integrated offerings spanning solid and hollow stabilizer bars and links, including active damping variants for passenger and commercial vehicles. Its strategic move to form a joint venture with Wolong Electric Group Co., Ltd. to manufacture electric motors for driveline and stabilizer systems indicates an intention to embed stabilizer technology deeper into electrified platform architecture. The signal is clear: stabilizer systems are increasingly connected to driveline and energy management strategies, and suppliers that can bridge mechanical and electromechanical domains may capture more value.
Mubea Group continues to emphasize precision manufacturing across passenger cars, light trucks, and commercial vehicles, a positioning that suits customers seeking consistent tolerances and reliability across diverse vehicle types. Kongsberg Automotive and Sogefi Group both serve OEM integration in passenger cars and light commercial vehicles, with Sogefi extending into heavy-duty applications where durability and load capacity carry greater weight. These profiles illustrate a broader split between generalists with integrated portfolios and specialists with deep segment knowledge.
thyssenkrupp AG adds a differentiated angle through lightweight aluminum and high-strength steel variants, targeting OEMs that need weight reduction without sacrificing strength. ADDCO Manufacturing Company and SwayTec focus on performance-oriented and aftermarket applications in the U.S., where polymer bushings and reinforced designs address durability and handling in both standard and specialty use cases. Tinsley Bridge Group rounds out the landscape by serving OEM and aftermarket passenger and commercial vehicle suspension, showing that dual-channel strategies can buffer against OEM cycle volatility.
Worldwide Automotive Stabilizer Bar Link Market
Recent developments reinforce the directions already visible in product roadmaps. The JV between ZF and Wolong in November 2025 points toward electrification-driven integration, while the U.S. Defense Logistics Agency procurement solicitation in December 2025 for stabilizer bars under a fleet sustainment set-aside signals that durable, serviceable components remain relevant in government and specialty fleet contexts. These events show that the market is not only commercial; it also includes institutional demand channels where specification, traceability, and longevity matter as much as price.
Strategic implications differ by positioning. Integrated players are leveraging cross-component engineering and electrification partnerships to capture more system value. Lightweight specialists are betting that aluminum and high-strength steel will become more central as emissions and efficiency targets tighten. Aftermarket and performance-focused companies are differentiating through application tuning, corrosion resistance, and reinforcement, where brand trust and fitment accuracy can command premiums. The broader trend is a mix of consolidation among players seeking scale and platform leverage, alongside fragmentation in niches where specialized materials, regional service needs, or performance characteristics create barriers to generic competition.
Future Outlook and Commercial Opportunities
Over the next three to five years, three trends are likely to shape where value concentrates. The first is the accelerating integration of lightweight materials with suspension architecture, especially in electric and hybrid platforms. As battery mass and packaging constraints continue to reshape vehicle dynamics, hollow stabilizer bars, aluminum variants, and high-strength steel grades will see increased adoption in programs where weight savings directly support range, handling, and packaging goals. The commercial opportunity lies in offering modular designs that can be tuned across derivatives without excessive tooling duplication, allowing OEMs to scale lightweight solutions across multiple nameplates.
PW Consulting
The second trend is rising demand for corrosion-resistant and climate-adapted components. Advanced surface treatments and material selections that withstand harsh climates are becoming differentiators not only for durability but also for warranty costs and brand reputation. For suppliers, this creates an opening in regions with severe winter conditions, coastal environments, or heavy-duty service cycles, where premium coatings and treatment processes can command higher margins and reduce total cost of ownership for fleets and consumers alike.
The third trend is the gradual move toward smarter and more integrated suspension components, particularly in higher-tier platforms. Active damping variants and parametrically tuned links are unlikely to become universal, but they will expand in premium passenger cars and selected commercial applications where handling precision and occupant experience are central to positioning. The opportunity here is for suppliers that can integrate stabilizer technology with electronic control strategies, sensor feedback, or modular linkage designs, provided they can manage increased complexity and validation costs.
These trends come with risks. Aluminum price swings can erode the economics of lightweight designs if hedging, sourcing, or design flexibility is insufficient. Regulatory endpoints may shift, altering the pace of lightweighting mandates and the relative attractiveness of certain material choices. Platform consolidation by automakers can reduce the number of discrete programs, making volume concentration a double-edged sword. Finally, electrification introduces durability unknowns for components under continuous high-torque and altered load patterns, which can surface late in a program if validation and testing are rushed. Companies that treat these risks as design and sourcing parameters rather than external shocks will be better positioned to protect margins.
Strategic Actions for Decision Makers
For manufacturers, the priority is to align material and architecture roadmaps with where vehicle platforms are moving. That means investing in hollow and aluminum-capable processes where volume and program mix justify them, while maintaining strong steel-based offerings for cost-sensitive and heavy-duty applications. It also means building corrosion-resistant and climate-adapted variants as standard options rather than custom exceptions, since durability expectations are rising across regions. Developing integration capabilities, including active or semi-active damping elements and link designs that support modular platforms, will help capture more value from OEMs seeking to reduce component count and simplify assembly.
For investors, the most relevant signal is that growth is shifting toward engineered differentiation rather than pure volume expansion. Companies with strong material engineering, regional manufacturing flexibility, and evidence of integration into electrified or lightweight platform programs are better placed to defend margins through raw material volatility and regulatory change. Attention should also be paid to dual-channel players that balance OEM programs with aftermarket or specialty fleet demand, since these channels can cushion program concentration risk. Monitoring recent strategic moves such as electrification-linked partnerships and procurement activity in institutional channels can provide early indications of where demand will intensify.
For procurement and sourcing leaders, the key is to treat stabilizer bar sourcing as a risk-managed engineering decision rather than a commodity purchase. Evaluating suppliers on corrosion resistance, tolerance consistency, material flexibility, and regional production capability can reduce downstream warranty and service issues. Where programs are exposed to aluminum price volatility, structured sourcing with hedging options, dual material strategies, or configurable designs can preserve cost predictability without sacrificing performance targets. In fleet and institutional contexts, durability, traceability, and sustainment support may outweigh lowest initial price, making total lifecycle cost the more relevant evaluation frame.
The market’s next phase will reward companies that can translate regulatory pressure, electrification-driven packaging constraints, and material volatility into practical product architectures and sourcing strategies. Detailed segment data, regional demand patterns, material mix modeling, and customized company benchmarking can sharpen those decisions further. PW Consulting’s full research report provides a deeper breakdown of regional demand trends, type and application dynamics, and supplier positioning to support more precise planning and investment choices.
For detailed analysis of this topic, please visit the official page: Automotive Stabilizer Bar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Wheel Balancer Market: How 4.1% CAGR and Regional Shifts Redefine Competition
By PW Consulting, 2026-09-21
Wheel Balancer Market: Strategic Trends and Commercial Opportunities in a Maturing Industry
The global wheel balancer market has entered a phase of steady, structurally supported expansion. Between 2020 and 2025, industry revenue climbed from approximately $183.0 million to $242.0 million, reflecting consistent demand across aftermarket service networks, fleet maintenance operations, and dealership service bays. Looking ahead to 2032, the market is projected to reach roughly $320.0 million, translating to a compound annual growth rate of approximately 4.1 percent over the forecast period. While the trajectory is unspectacular in headline terms, the underlying dynamics reveal a sector undergoing meaningful technological and operational transformation. For executives, investors, and procurement leaders, the opportunity lies not in chasing volume growth alone, but in understanding where efficiency, precision, and regulatory alignment are reshaping competitive positioning.
The current landscape reflects a mature but evolving equipment category. Wheel balancing has transitioned from a purely mechanical calibration task to a digitally assisted, automation-friendly process that directly impacts service throughput, tire longevity, and vehicle safety compliance. Producers and service operators alike are responding to tighter workshop margins, skilled labor constraints, and rising customer expectations for faster, repeatable results. At the same time, the market is not immune to friction points. Supply chain volatility for precision components, uneven adoption of advanced balancing technologies across regions, and the cost of integrating new automation features create real barriers for mid-tier manufacturers and independent shops. These pressures are not temporary disruptions; they are structural conditions that will define which players capture margin expansion and which remain trapped in price competition.
One of the most pressing challenges is the tension between automation momentum and workforce realities. Service centers face persistent technician shortages and rising labor costs, yet retrofitting older balancing equipment or training staff on hands-off systems requires capital and change management that many operators delay. A second challenge centers on standardization and compliance complexity. Workshop equipment must navigate overlapping safety and quality frameworks, and balancing accuracy is increasingly tied to mandatory periodic technical inspections in multiple jurisdictions. Operators that treat balancing as a discretionary service risk losing credibility with fleet buyers and inspection-dependent customers. A third challenge lies in product differentiation. As baseline balancing performance becomes table stakes, manufacturers must demonstrate measurable gains in changeover speed, error reduction, or fleet-level vibration control without pushing prices beyond what service operators can justify through labor savings. These challenges create a clear inflection point: the next cycle of growth will reward companies that align product design, service workflows, and compliance readiness rather than those that compete solely on unit price.
Key Drivers Reshaping the Wheel Balancer Market
Technology Innovation and Precision Automation
The most visible driver of market evolution is the shift toward automation and sensor-enhanced precision. Modern wheel balancers are increasingly designed to reduce manual intervention, compress cycle times, and standardize results across operators with varying experience levels. Hands-off inflation, automatic weight detection, and integrated tire-changing workflows are no longer niche 프리미엄 features; they are becoming central to high-volume service economics. Recent product introductions illustrate this direction. In October 2025, Hunter Engineering Company introduced a Road Force WalkAway wheel balancer with an automatic hands-off inflation system that reduced four-tire changeover times by up to 45 percent, and the same platform was demonstrated alongside an integrated Revolution tire changer at SEMA Show 2025. Around the same period, ARI-Hetra launched a heavy-duty line featuring Tri-Sensor Technology and LCD displays aimed at improving workshop precision. These developments signal a broader industry move toward closed-loop balancing processes where measurement, correction, and verification are tightly integrated.
For service operators and equipment buyers, the strategic implication is straightforward: automation is being evaluated less as a convenience and more as a labor multiplier. Shops that can standardize balancing output while reducing technician fatigue gain advantages in throughput, consistency, and customer trust. For manufacturers, the challenge is to ensure that advanced features translate into demonstrable operational savings rather than added complexity or maintenance burden. The market is therefore rewarding platforms that combine intuitive interfaces, reliable sensor performance, and seamless integration with adjacent tire service equipment.
Policy and Regulatory Environment
Regulatory and safety standards are increasingly shaping purchasing decisions and equipment design. Workshop equipment, including wheel balancers, operates under a framework of occupational safety, product certification, and quality management expectations that vary by region but converge on the same principle: balancing accuracy and operator protection are non-negotiable. Mandatory periodic technical inspections under systems such as TÜV and MoT regulations reinforce the need for accurate wheel balancing as part of vehicle safety compliance. At the same time, OSHA, CE, and ISO standards continue to influence how tire handling equipment is specified, installed, and maintained in professional environments.
This regulatory layer is not merely a compliance checkbox; it is a market filter. Fleet managers, dealership groups, and regional service chains are more likely to standardize on equipment that aligns with recognized safety and quality expectations because it reduces audit exposure, simplifies technician training, and supports consistent inspection outcomes. For manufacturers, regulatory alignment has become a competitive differentiator, especially in markets where inspection regimes are tightening and where service providers must demonstrate repeatable, documented balancing performance.
Wheel Weight Market
Demand-Side Shifts in Aftermarket and Fleet Service
Demand for wheel balancing is being reshaped by changes in how vehicles are maintained and how service time is valued. Passenger vehicle segments continue to represent the largest application share, driven by high vehicle parc, frequent tire rotations, and consumer sensitivity to ride quality and tire wear. Commercial vehicle operations, while smaller in volume terms, are expanding their reliance on advanced balancing solutions because fleet downtime, fuel efficiency, and vibration-related component wear carry direct operational costs. In both segments, the value proposition is shifting from balancing as a standalone service to balancing as part of a broader efficiency and safety workflow.
Fleet adoption is particularly telling. IMI Products received approval from UPS for its Equal FLEXX wheel balancer under the 2026 Tire Solutions Program following a two-year field evaluation with over 10,000 assemblies. This type of endorsement matters because it moves balancing technology from theoretical benefit to validated operational performance in a high-mileage, cost-sensitive environment. Fleet buyers are increasingly willing to evaluate internal adaptive balancing systems and other specialized solutions when they can tie them to measurable outcomes such as vibration reduction and fuel efficiency improvements. The broader lesson for the market is that demand is becoming more evidence-driven, and suppliers that can document real-world performance will have an advantage in both fleet and high-volume aftermarket channels.
Supply Chain and Cost Structure Dynamics
Cost structure and supply chain resilience remain critical underlying drivers. Precision balancing equipment depends on reliable sourcing of sensors, electronics, machining components, and durable mechanical assemblies. Inflationary pressure on materials, lead-time variability, and the cost of integrating digital features can compress margins for manufacturers and raise total cost of ownership for buyers. At the same time, rising labor intensity in service environments is changing how total costs are evaluated. Service operators are increasingly comparing the upfront price of a balancer against its impact on technician utilization, rework rates, and service cycle time.
This shift is pushing both sides of the market toward more holistic cost assessments. Manufacturers that can stabilize production, reduce dependency on fragile component pathways, and design equipment that is easier to service and calibrate gain credibility with buyers who are managing both capex and opex constraints. For purchasers, the decision framework is moving toward lifecycle value: equipment that lowers labor intensity, reduces error-related rework, and supports faster turnaround can justify a higher initial investment. In a market where labor shortages and throughput demands are persistent, cost discussions are increasingly anchored in operational efficiency rather than sticker price alone.
Competitive Landscape and Leading Strategies
The wheel balancer market is characterized by a moderately concentrated competitive structure, with the top three players holding roughly 45 percent of market share and the top five accounting for about 55 percent. This concentration suggests that established manufacturers retain significant influence over product standards, channel relationships, and customer expectations, while still leaving meaningful space for regional specialists and integrated equipment providers. The leadership group reflects a mix of long-standing diagnostic and heavy-duty balancer expertise, broad tool and equipment portfolios, and manufacturers that emphasize vibration analysis, alignment compatibility, or fleet-specific internal balancing technologies.
PW Consulting
Hunter Engineering Company continues to reinforce a leadership position centered on diagnostic-grade balancing and workflow integration. Its focus on automatic inflation, hands-off procedures, and integrated tire changer demonstrations points to a strategy built around reducing changeover time and standardizing results in high-throughput environments. Coats Company LLC has carved a strong position in heavy-duty direct drive balancing, targeting high-volume tire service operations where durability, speed, and repeatability are paramount. Snap-on Incorporated leverages its broader professional tool footprint to serve high-volume shop use, aligning wheel balancers with a wider ecosystem of workshop equipment and service reliability expectations. CEMB S.p.A. brings a garage and truck-oriented perspective, with product emphasis on vibration analysis integration and touchless alignment compatibility, which positions it well in markets where multi-function workshop efficiency matters. IMI Products differentiates through internal adaptive balancing systems designed for fleet truck tires, focusing on vibration reduction and fuel efficiency improvements rather than conventional external balancing alone. Balance Group represents a more integrated equipment approach, offering wheel balancers within a broader tyre service equipment lineup that spans car, motorcycle, truck, and heavy-duty wheels, appealing to operators seeking unified sourcing and service compatibility.
These differing strategic positions reveal how the market is fragmenting by use case while still rewarding clear differentiation. Leadership is no longer defined solely by balancing accuracy in isolation; it is increasingly defined by how well a product fits into a specific operating model. Heavy-duty commercial service providers value durability and throughput. Fleet operators value documented operational outcomes. Dealership and high-volume aftermarket shops value speed, consistency, and integration. Manufacturers that can articulate and deliver a distinct workflow advantage are better positioned than those offering generic balancing capability.
The competitive landscape is also evolving through a combination of consolidation pressure and targeted new entry. Larger players benefit from scale, channel reach, and the ability to invest in automation and compliance-driven design, but they must navigate the complexity of serving diverse segments without diluting their value proposition. Smaller or regional manufacturers can compete by focusing on specific vehicle classes, localized service support, or integrated equipment bundles that reduce procurement friction. At the same time, new entrants that bring novel sensor architectures, improved display and user-interface design, or fleet-validated internal balancing concepts can gain traction if they address a clearly defined operational pain point. The overall trend points toward a market where differentiation is increasingly tied to workflow fit, validated performance, and total cost of ownership rather than brand familiarity alone.
Future Trends and Strategic Implications
Over the next three to five years, the wheel balancer market is likely to be shaped by three interconnected trends. The first is the deepening integration of automation and workflow standardization. As service operators continue to face labor constraints and throughput pressure, equipment that minimizes manual steps, reduces changeover variability, and supports repeatable results will become increasingly central to shop economics. This trend will likely accelerate the adoption of hands-off balancing features, integrated tire service workflows, and easier calibration routines, especially in high-volume environments. The commercial opportunity here lies in equipment and service models that help operators quantify labor savings, reduce error-related rework, and maintain consistent output across different technicians and shifts.
The second trend is the growing importance of fleet-validated and application-specific solutions. As fleet managers and commercial operators look for tangible gains in vibration control, tire life, and fuel efficiency, internal adaptive balancing and heavy-duty precision systems are likely to receive stronger evaluation and adoption in targeted segments. This creates an opportunity for manufacturers to build credibility through field trials, documented performance data, and partnerships with large fleet programs. It also suggests that generic balancing claims will face greater scrutiny, while solutions backed by operational evidence will command stronger consideration in commercial and high-mileage applications.
The third trend is the continued alignment of equipment purchasing with regulatory and inspection-driven compliance expectations. As periodic technical inspection regimes and workshop safety standards remain influential, balancing accuracy and equipment reliability will stay closely tied to service credibility and operational risk management. Manufacturers and service providers that proactively design for compliance, documentation, and consistent performance will be better positioned to win standardized contracts, dealership network agreements, and fleet maintenance programs. The related risk is that operators who underinvest in balancing quality or rely on outdated equipment may face growing inconsistency in inspection outcomes, technician training burdens, and customer trust.
These trends carry both opportunity and uncertainty. On the opportunity side, the market is moving toward clearer value metrics: cycle-time reduction, labor efficiency, vibration-related performance, and compliance readiness. Providers that can connect product capabilities to these outcomes are more likely to capture premium positioning and repeat business. On the risk side, adoption pace may vary by region and shop size, and the cost of upgrading equipment or retraining staff can slow momentum for smaller operators. Additionally, if automation features become widespread without meaningful differentiation, competition could shift back toward price, squeezing margins for manufacturers that fail to sustain a distinct workflow advantage. The most resilient strategies will therefore combine technological relevance with practical evidence, clear segmentation, and a credible pathway to total cost reduction for the buyer.
Worldwide Wheel Balancer With Touchscreen Market
Actionable Recommendations for Decision Makers
For manufacturers and product strategists, the priority is to sharpen differentiation around workflow outcomes rather than balancing performance alone. This means designing for measurable labor savings, integrating balancing with adjacent tire service steps where it improves throughput, and ensuring that automation features are easy to adopt, maintain, and calibrate. Companies should also invest in field-validated documentation, especially for commercial and fleet applications, because evidence of vibration reduction, fuel efficiency improvement, or assembly-level consistency can become a decisive factor in procurement decisions. Finally, maintaining regulatory and safety alignment as a core design principle will help reduce friction in inspection-heavy markets and in standardized service networks.
For investors and strategic planners, the most relevant signal is that growth in this market is likely to be earned through efficiency and application fit rather than broad-based volume expansion. Opportunities may be strongest in companies that serve high-volume aftermarket and fleet workflows, offer clear automation advantages, and have product lines aligned with commercial vehicle and heavy-duty needs. At the same time, caution is warranted where product portfolios lack segmentation clarity, where automation claims are not tied to operational savings, or where supply chain and service support are weak. Evaluating total cost of ownership, channel strength, and the credibility of field performance data will be more informative than relying on headline market growth alone.
For procurement leaders and service operators, the practical imperative is to evaluate balancing equipment as a productivity investment rather than a commodity purchase. Selection criteria should include changeover speed, repeatability across technicians, integration with existing tire service workflows, and the availability of service support and calibration resources. Where fleet or commercial vehicle use is significant, internal adaptive systems and heavy-duty solutions deserve structured evaluation against documented operational outcomes. Operators should also consider how equipment choices affect inspection readiness, technician training burden, and long-term service consistency, since these factors increasingly influence overall workshop economics.
For decision makers seeking a deeper understanding of segment-level demand patterns, regional variations, pricing dynamics, and company-specific competitive positioning, the full research report provides the detailed breakdown needed to support planning and procurement decisions. It offers a more granular view of how product types, application segments, and regional markets interact, along with customized guidance for aligning equipment strategy with operational goals. Accessing that level of detail can help teams move from broad market awareness to targeted action, especially when evaluating new product roadmaps, fleet adoption programs, or service-shop upgrade cycles.
For detailed analysis of this topic, please visit the official page: Wheel Balancer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Isononyl Alcohol Market: Why 5.55% CAGR Changes Everything Through 2032
By PW Consulting, 2026-09-21
Isononyl Alcohol Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The isononyl alcohol market has matured into a cornerstone of specialty chemical supply chains, anchored by consistent growth in plasticizer and surfactant applications. Valued at approximately $1.5 billion in 2025, the market has expanded steadily over the past half-decade, with historical revenues climbing from $1.2 billion in 2020 to current levels. Forecasts indicate a continued upward trajectory, projecting revenues to surpass $2.1 billion by 2032 at a compound annual growth rate of 5.55 percent. This growth pattern reflects both cyclical demand recovery and structural shifts toward higher-performance, non-phthalate intermediates.
Behind the headline figures, the industry confronts several pivotal challenges that will shape competitive positioning over the next decade. The first is the tension between cost efficiency and sustainability compliance. As regulatory frameworks tighten and end-use customers demand verified circular sourcing, producers must justify capital expenditures for bio-based feedstocks, traceable supply chains, and certified manufacturing processes without sacrificing margin performance.
The second challenge lies in demand concentration and substitutability risk. A significant share of isononyl alcohol consumption flows into plasticizer formulations, where formulation engineers continuously evaluate alternatives such as alternative oxo alcohols, bio-derived esters, and phosphate-based systems. Suppliers cannot rely on legacy volume assumptions; they must demonstrate differentiated performance, regulatory readiness, and supply reliability to retain share in evolving formulations.
The third challenge is geographic and capacity imbalance. Production capacity remains clustered among a handful of integrated manufacturers, while demand growth is accelerating in regions with expanding PVC processing, personal care manufacturing, and industrial lubricant consumption. New capacity additions in East Asia and Southeast Asia are reshaping supply dynamics, but they also intensify competition for feedstock access, logistics optimization, and customer qualification. These pressures create a market where incumbents must defend margins through operational excellence and sustainability credentials, while newer entrants seek footholds through technology licensing, strategic partnerships, and targeted application specialization.
Key Demand Drivers
Several interconnected forces are steering the market’s direction, and each carries distinct implications for sourcing strategies, capacity planning, and product development.
Technological Innovation and Process Differentiation
Advancements in oxo synthesis and hydroformylation continue to redefine quality parameters and cost structures. Modern catalyst systems, improved isomer control, and integrated downstream purification enable producers to deliver higher-purity grades suitable for sensitive applications, including specialty esters and electronics-adjacent formulations. Process refinements also support narrower specification ranges, which matter for downstream formulators seeking consistent plasticizer performance and reduced variability in surfactant blends. Manufacturers that pair process reliability with flexible grade portfolios are best positioned to capture premium segments and reduce the cost of customer qualification.
A parallel wave of innovation centers on sustainability-linked production. Certification frameworks and circular sourcing commitments are moving from optional differentiators to operational requirements. Recent certification activity at major production sites signals that sustainable sourcing and circular economy compliance are becoming embedded in commercial offerings rather than remaining aspirational. For buyers and partners, this shifts the conversation from whether a supplier can provide certified material to how consistently it can do so across volumes and geographies.
Regulatory and Compliance Evolution
Regulatory oversight remains a decisive factor in formulation choices and supply chain design. Registration and compliance documentation for isononyl alcohol underpin its continued use in plasticizers and related applications, giving formulators confidence in long-term availability. At the same time, the broader regulatory environment is nudging the market away from traditional phthalate architectures and toward alternatives that preserve performance while meeting evolving safety and environmental expectations. This does not eliminate isononyl alcohol’s role; rather, it reinforces its position as a versatile intermediate when paired with compliant manufacturing practices and transparent documentation.
The practical impact is twofold. First, compliance readiness becomes a competitive asset, particularly for suppliers serving multiple jurisdictions with differing registration and traceability requirements. Second, the regulatory trajectory encourages investment in grades and processes that can adapt to reformulated end products, reducing the risk of stranded capacity as customer specifications change.
Demand-Side Shifts in End-Use Industries
Demand patterns are being reshaped by formulation trends in plastics, personal care, and industrial lubricants. In plasticizer applications, the push toward non-phthalate and high-performance alternatives sustains interest in isononyl alcohol as a building block for DINP and related systems, especially where flexibility, durability, and processing characteristics remain critical. In personal care and fragrance-adjacent uses, formulators are seeking emollient ingredients that offer consistent skinfeel and stability, driving niche but high-value demand for specialty grades. Lubricant applications add another layer of demand resilience, as industrial and automotive segments pursue formulations that balance performance with extended drain intervals and efficiency goals.
These demand-side shifts reward suppliers that can offer application-specific grades, technical support, and reliable lead times. The market is increasingly less about commodity volume alone and more about the ability to match grade attributes to formulation requirements, which in turn supports more stable pricing and deeper customer relationships.
Supply Chain and Cost Structure Dynamics
Cost structures are influenced by feedstock availability, energy pricing, and the geographic distribution of production assets. Integrated producers with access to reliable olefin streams and efficient hydroformylation operations hold a structural advantage in managing input cost volatility. At the same time, regional capacity additions are altering logistics patterns, with new facilities positioned to serve fast-growing demand centers and reduce freight exposure for local customers.
Capacity expansion announcements, including large-scale projects utilizing established technology licenses, indicate that supply will continue to broaden in key regions. These developments can improve availability and create competitive price tension, but they also place a premium on qualification speed, supply consistency, and technical service. In practical terms, the cost equation is no longer determined solely by feedstock prices; it increasingly reflects the value of certified continuity, grade flexibility, and regional proximity to demand.
Competitive Landscape and Leading Strategies
The market features a concentrated group of global manufacturers alongside regional specialists and new capacity entrants. Leading firms differentiate through a combination of process technology, grade breadth, certification readiness, and application-focused commercial support. Their strategic positioning offers a useful lens for understanding where value is being created and how the landscape is likely to evolve.
Strategic Positioning of Core Players
German-based producers have strengthened their standing by combining integrated oxo alcohol capabilities with a focus on sustainability certification and application breadth. One major manufacturer operates isononyl alcohol production tied to its C4 chemicals platform, supplying plasticizer and surfactant grades through hydroformylation of C8 olefins, and has reinforced its sustainability positioning through certification valid through mid-2026. Another industry leader leverages partnership structures and its own facilities to serve plasticizer applications at scale, supported by ongoing regulatory compliance documentation that facilitates use across multiple markets.
Specialty oxo intermediates producers have built reputation on grade consistency and global distribution, offering both plasticizer and specialty chemical grades that serve diverse formulation needs. In the United States, large chemical companies provide isononyl alcohol through established oxo processes at major complexes, with emphasis on DINP and high-purity plasticizer applications. One North American supplier focuses on specialty esters and non-phthalate plasticizer supply, aligning its offering with shifting formulation preferences. In Asia, integrated producers with large complexes supply PVC plasticizer grades for domestic and export markets, benefiting from regional demand growth and logistics advantages.
Additional players contribute to the landscape through portfolio breadth and targeted application focus. A Swedish producer offers isononyl alcohol within a broader C8-C10 oxo alcohol portfolio for plasticizers and lubricants, while a Japanese manufacturer supports high-purity grades for electronics and automotive uses through licensed oxo processes. A South African producer supplies the chemical within its oxo alcohol portfolio for plasticizer and surfactant applications. Most recently, a major Chinese refining and chemical company has moved to build a world-scale isononyl alcohol facility using licensed technology, with startup targeted for 2026, signaling a meaningful addition to regional supply.
Isononanoic Acid Market
Differentiation Themes and Competitive Advantages
Across these players, differentiation converges on a few recurring themes. Process control and grade purity are foundational, particularly for customers in sensitive applications where specification consistency reduces downstream risk. Sustainability certification and traceable sourcing are increasingly weighted in supplier selection, especially where end customers require documented circular economy alignment. Commercial agility matters as well: producers that can balance large-volume plasticizer supply with specialty grades and provide technical support are better equipped to retain customers during formulation changes.
Regional presence and logistics efficiency also shape advantage. Suppliers with production assets close to fast-growing demand centers can reduce lead times and freight exposure, while those with global distribution networks can serve multinational customers more consistently. Finally, technology licensing and partnership models are enabling new capacity to enter the market with established process knowledge, accelerating scale-up and reducing execution risk relative to wholly custom development paths.
PW Consulting
Evolving Market Structure
The competitive structure is gradually shifting from a purely incumbent-centric model to one that balances established scale with targeted new entry. On one side, large incumbents are defending their positions through certification, application focus, and integration benefits. On the other, new capacity in Asia and Southeast Asia is expanding regional supply and intensifying competition for both volume and specialty demand. This does not necessarily imply a race to the bottom; rather, it suggests a market where differentiation narrows the field. Customers are likely to consolidate spending with suppliers that can demonstrate reliable certification, consistent grade quality, and strong technical support, while price competition intensifies in commoditized segments.
Over time, this dynamic may encourage further consolidation among smaller players lacking scale or certification readiness, while rewarding those that can combine capacity with application expertise. The emergence of large, licensed facilities also raises the importance of customer qualification pipelines and long-term supply agreements, as new volumes must be absorbed into established formulation ecosystems.
Worldwide Isononyl Acrylate Market
Forward Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to define the market’s trajectory and open practical opportunities for aligned businesses.
Sustainability-Linked Supply as a Commercial Baseline
Certified, traceable production is expected to move from advantage to baseline expectation in many customer segments. As procurement teams embed sustainability criteria into supplier evaluation, producers with valid certifications and documented circular sourcing will face lower barriers to qualification and retention. Commercial opportunities here include premium-grade offerings that pair performance with compliance, long-term supply arrangements that reward certified continuity, and regional partnerships that reduce the logistical footprint of sustainable supply. The risk is that capability gaps in certification or traceability could limit access to certain customer segments, especially where end-market requirements are stringent.
Grade Specialization and Application-Focused Targeting
The market is likely to reward narrower, application-specific grade strategies over undifferentiated volume plays. In plasticizer formulations, high-purity and performance-tuned grades will remain important where formulators seek predictable processing and end-product characteristics. In personal care, fragrance, and lubricant applications, specialty grades that meet specific sensory, stability, or efficiency requirements can command stronger positioning. Businesses that invest in grade flexibility, technical service, and customer co-development are better placed to capture value in these segments. The uncertainty lies in the pace of formulation change: if alternative chemistries gain traction faster than expected in certain applications, suppliers must be ready to adapt grade portfolios without overcommitting to legacy demand assumptions.
Regional Capacity Rebalancing and Supply Chain Reconfiguration
New capacity additions in East Asia and Southeast Asia will continue to reshape supply geography, creating opportunities for regional price competitiveness, faster service, and reduced logistics risk for nearby customers. For buyers, this can translate into more options for local sourcing and improved resilience. For suppliers, it raises the stakes in qualification speed, distribution capability, and customer relationship depth. The risk is that rapid capacity additions could create temporary oversupply in specific regions or grades, pressuring margins unless offset by demand growth or differentiated offerings. Strategic positioning will depend on aligning capacity with demand centers while maintaining cost discipline and certification readiness.
Actionable Guidance for Decision-Makers
Different stakeholders face distinct priorities, but a few strategic actions apply broadly and can help convert market trends into tangible outcomes.
-
Manufacturing and supply leaders should prioritize certification continuity and grade flexibility as core commercial assets. Maintaining valid sustainability certification, strengthening documentation for regulatory compliance, and expanding the ability to supply application-specific grades can improve qualification speed and customer retention. Where possible, align production and logistics with regional demand growth to reduce lead times and freight exposure.
-
Investors and corporate development teams should evaluate opportunities through the lens of differentiation rather than scale alone. Capacity additions that pair licensed process technology with sustainability credentials and application focus are more likely to secure qualified demand than undifferentiated volume projects. Attention to customer qualification pipelines, regional demand timing, and downstream formulation trends can materially affect the risk-adjusted returns of new capacity or partnership investments.
-
Procurement and sourcing professionals should build supplier evaluation frameworks that weigh certified continuity, grade consistency, and technical service alongside price. In a market where regulatory compliance and sustainability documentation are increasingly important, multi-source strategies that include both scaled incumbents and regionally positioned suppliers can improve resilience. For critical applications, securing long-term arrangements with suppliers able to demonstrate stable certification and consistent specifications can reduce disruption risk and support formulation stability.
The isononyl alcohol market is entering a phase where growth is real but value capture depends on execution quality. Sustainability certification, grade specialization, regional supply strategy, and application-focused technical support are becoming central to competitive success. Businesses that treat these elements as strategic priorities, rather than operational afterthoughts, will be better positioned to navigate demand shifts, regulatory evolution, and new capacity entry.
For organizations seeking deeper segmentation data, regional demand profiles, and customized scenario analysis, PW Consulting’s full market research report provides detailed breakdowns and tailored recommendations to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Isononyl Alcohol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Forging Presses Market 2026-2032: Inside the 4.3% CAGR and $281M Expansion
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Forging Presses Market
Market Overview and Core Challenges
The global forging presses market has demonstrated resilient, steady growth over the past half-decade, expanding from approximately 145.78 million USD in 2020 to an estimated 208.45 million USD in 2025. This trajectory reflects an underlying compound annual growth rate of 4.3 percent through the forecast period ending in 2032, when revenues are projected to reach 280.9 million USD. The market's expansion is not explosive, but it is structurally supported by fundamental industrial needs: the transformation of raw metal into high-strength, precision-shaped components remains indispensable across transportation, energy, and manufacturing sectors. Growth is being shaped less by cyclical surges and more by a steady accumulation of capacity upgrades, modernization programs, and the gradual migration toward higher-value forming technologies.
A defining characteristic of the current landscape is the widening gap between mature regional markets and those experiencing accelerated industrial investment. North America and Europe continue to anchor significant portions of market value, but Asia Pacific has emerged as the dominant geographic contributor to total market size, reflecting large-scale manufacturing expansion, infrastructure development, and growing domestic demand for forged components across automotive, heavy equipment, and industrial machinery supply chains. Latin America and the Middle East and Africa represent smaller but strategically relevant pockets of activity, often tied to localized industrial policy, resource-based manufacturing, and targeted capital projects. This geographic distribution is reshaping how equipment suppliers think about regional service footprints, localized support, and the balance between standardized offerings and region-specific configuration requirements.
Beneath the growth narrative, three structural challenges are redefining competitive dynamics and forcing strategic recalibration among manufacturers and end-users alike.
Fragmented Value Chains and Regional Capacity Gaps
While aggregate market figures suggest orderly growth, the underlying supply chain remains uneven. Many forging operations face bottlenecks in sourcing high-quality dies, specialized auxiliary equipment, and integrated automation modules. These gaps are not merely procurement inconveniences; they create execution risk for large press installations and complicate delivery timelines for operators trying to align new capacity with production schedules. The result is a market in which vendors capable of bundling presses with dies, handling systems, and control integration are gaining an advantage over those offering machine-only solutions. For end-users, this fragmentation raises the stakes of vendor selection, because the total installed capability of a forging line now depends on more than the press itself.
Energy Intensity and Efficiency Mandates
Forging presses are energy-intensive assets, and environmental as well as operational pressures are pushing the industry toward measurable efficiency gains. Regulatory expectations and internal sustainability targets increasingly require facilities to adopt technologies that deliver substantial reductions in energy consumption relative to conventional systems. This shift is not simply a compliance exercise. It is becoming a financial and operational differentiator, especially in regions where electricity costs, carbon exposure, or industrial energy policies are tightening. Presses that can recover kinetic energy, modulate power delivery more precisely, or integrate hybrid hydraulic-electric architectures are moving from niche innovation to practical necessity for operators seeking lower operating costs and greater production predictability.
Cold Forging Machine Market
Labor Constraints and Automation Pressure
Another persistent challenge is the availability of skilled labor for press operation, die setup, and process supervision. In several major forging markets, workforce constraints are accelerating investment in automation, digital control systems, and tool-less changeover strategies that reduce dependence on specialized manual intervention. This trend is reshaping equipment requirements: buyers are increasingly prioritizing press platforms that can integrate easily with automated material handling, in-process monitoring, and adaptive control logic. At the same time, the transition introduces a new form of complexity. Automation is not automatically plug-and-play, and the value of a press investment increasingly depends on how well it fits within a broader digitized production environment rather than on raw tonnage or stroke speed alone.
Key Drivers Shaping Market Evolution
The market's growth and direction are being pulled by a small set of powerful drivers that reinforce one another. These forces are not isolated trends; they interact to create pressure on legacy designs, reward certain technology pathways, and influence where capital is deployed next.
Mechanical Presses Market
Technology Innovation in Press Architecture and Energy Recovery
One of the most significant enablers of market change is the ongoing refinement of press architectures. Mechanical, hydraulic, and servo-based systems continue to coexist, but the competitive center of gravity is shifting toward designs that combine performance with lower energy input and greater process flexibility. Advanced systems now incorporate energy recovery mechanisms, hybrid drive configurations, and more responsive control architectures that allow manufacturers to run higher stroke rates while reducing waste heat and idle power draw. These innovations are not merely engineering achievements; they have commercial implications. They expand the range of applications that can be economically served by a single press platform, improve consistency in closed-die and open-die operations, and help manufacturers justify capital expenditure in an environment where operating cost and sustainability performance are under closer scrutiny. Recent large-scale installations illustrate how these technologies are moving from pilot demonstrations into production use. A major global press supplier recently began production on what is described as the world's largest forging press equipped with a kinetic energy recovering system, signaling that energy recovery is being engineered into high-capacity assets rather than treated as a retrofit concept. Around the same time frame, another delivery highlighted a full hybrid hydraulic-electric press achieving meaningful energy reduction at an automotive facility, reinforcing the point that hybrid drive strategies are becoming commercially relevant for Tier-1 production environments.
Policy, Regulation, and Industrial Modernization Directives
Policy and regulatory frameworks are increasingly shaping technical expectations and investment timing. Energy efficiency mandates are pushing forging operations to incorporate technologies that deliver substantial consumption reductions compared with conventional systems, and these requirements are influencing both new equipment selection and retrofit strategies. In parallel, industrial modernization programs in several regions are encouraging capacity upgrades that emphasize automation, digital traceability, and process consistency. Forging press suppliers are responding by designing products that align more closely with compliance-related performance targets while also supporting broader modernization goals such as reducedManual intervention, better repeatability, and higher throughput stability. This regulatory and policy context matters because it affects not only whether a press is purchased, but what specifications are considered acceptable in the first place, and how quickly operators are willing to replace or augment older equipment.
Demand-Side Shifts in Automotive and Aerospace Production
Demand patterns from end-use sectors remain central to market direction. Automotive production continues to exert strong pull on forging demand, driven by the need for structural components, safety-critical parts, and lightweighting initiatives that still rely on forged geometries for strength-to-weight performance. Aerospace and related high-integrity applications also contribute meaningfully, where material properties, tolerance control, and process reliability are especially important. These sectors share a common orientation: they are not simply buying tonnage; they are buying predictable quality, repeatable process windows, and the ability to integrate forging into broader automated production flows. As a result, demand-side behavior is shifting toward suppliers and press configurations that can support higher volumes without sacrificing control, and that can demonstrate clear pathway to lower scrap, reduced rework, and tighter process adherence. The commissioning of a fully automatic closed-die forging press at a chain manufacturing operation in China illustrates how high stroke-rate automation is being applied to production environments that prioritize throughput and consistency, a pattern that is likely to become more common as manufacturers pursue cost efficiency and capacity utilization.
Supply Chain Restructuring and Cost Dynamics
Cost structures across the forging ecosystem are being reshaped by material usage patterns, labor economics, and the broader push toward integrated solutions. Carbon steel remains the dominant raw material basis in forging due to its balance of cost and strength, which keeps material sourcing and scrap management central to operational economics. At the same time, labor shortages in forging operations are encouraging greater reliance on automated press systems and digital controls to reduce personnel constraints. Together, these factors are nudging the market toward a model in which total cost of ownership, uptime, and process automation are weighed more heavily than initial purchase price. For suppliers, this means that value propositions are increasingly tied to integration, service responsiveness, and the ability to help customers manage energy, labor, and throughput simultaneously. For buyers, the implication is that the most competitive offer may not be the one with the lowest headline price, but the one that reduces operational drag over the asset's life cycle.
Competitive Landscape and Leading Strategies
The forging press market is competitive, but it is not perfectly consolidated. The top three competitors hold roughly 30 percent of market share, while the top five account for approximately 35 percent. This concentration suggests a landscape in which scale and reputation matter, yet substantial room remains for specialized players, regional experts, and firms that differentiate through technology, application focus, or integration capability. The competitive field is populated by a mix of established Western manufacturers, European technology leaders, Japanese equipment developers, and U.S.-based specialists serving a range of mechanical, hydraulic, warm-hot, and servo press applications.
Strategic Positioning Among Leading Players
A useful way to read the competitive field is by the strategic emphasis each group brings to the market. Some manufacturers have carved out strong identities around custom hydraulic solutions for open-die and closed-die applications, positioning themselves as flexible problem-solvers for customers with non-standard tonnage, configuration, or process requirements. These firms compete on engineering responsiveness, application-specific design, and the ability to adapt a press to the customer's production intent rather than selling a purely standardized machine. Other players focus on standard and custom hydraulic hot forging presses with high tonnage capabilities, appealing to customers who need large-scale forming capacity and want a defined technical baseline with room for customization. Still others extend their portfolios across mechanical, hydraulic, and servo technologies, often as part of broader industrial groups, which allows them to offer cross-technology guidance and to match press type to the production rhythm and process constraints of a given application. In parallel, some suppliers emphasize mechanical and servo press solutions for high-volume production, where speed, repeatability, and integration with automated lines are especially valuable. There is also a meaningful segment of firms that supply forging presses and related industrial forming equipment while positioning themselves as practical partners for metal forming operations, often competing on responsiveness, service support, and regional availability. Finally, a separate tier of custom hydraulic and servo press specialists supports extremely large forming requirements, giving high-tonnage customers access to tailored solutions that go beyond common commercial configurations.
The strategic takeaway is that competition is increasingly multidimensional. While tonnage, brand heritage, and machine class still matter, differentiation is being redefined by how well a vendor can align press technology with energy performance, automation readiness, application-specific process control, and delivery of a complete forming solution. The companies that appear best positioned are those that can articulate a clear technical identity while still offering enough flexibility to meet varying customer requirements across regions and end-use sectors.
PW Consulting
Recent Developments as Indicators of Direction
Recent activity among leading equipment suppliers offers a window into where the market is heading. One of the most notable signals is the growing emphasis on energy recovery and hybrid drive technologies in flagship installations. The start of production on a world-scale forging press featuring kinetic energy recovery, and the delivery of a hybrid hydraulic-electric press with documented energy reduction, both point to a direction in which efficiency is being designed into major assets at the engineering level rather than added later. Another important indicator is the successful commissioning of a fully automatic closed-die forging press achieving high stroke rates at a manufacturing site in China, which reflects the market's accelerating interest in automation, throughput maximization, and integrated closed-die forming capability. Participation in industry technical conferences and exhibitions also remains relevant, as it signals continued investment in customer engagement, technology demonstration, and ecosystem visibility. Taken together, these developments suggest that the competitive dialogue is shifting from machine capability alone toward integrated performance, energy behavior, automation compatibility, and the ability to execute complex installations in demanding production environments.
Market Evolution: Consolidation, Fragmentation, and New Entry
Looking ahead, the competitive structure is likely to evolve along several paths at once. Consolidation pressure exists at the top, where larger, globally capable suppliers can leverage breadth of technology, after-sales networks, and the ability to serve multinational customers with consistent standards. At the same time, fragmentation persists at the regional and application level, where local expertise, shorter decision cycles, and specialized configurations can create durable niches. New entry and repositioning are also possible, especially for firms that bring credible expertise in servo drive technology, energy-efficient press design, or integrated automation packages. The market is not simply moving toward a winner-takes-all structure; it is moving toward a layered competitive environment in which global scale, regional presence, and technology differentiation each create distinct forms of advantage.
Future Outlook and Strategic Opportunities
Based on current market data and visible technology and demand trajectories, three trends stand out as particularly important for the next three to five years.
Efficiency as a Core Buying Criterion
Energy performance is expected to move from an important attribute to a core buying criterion for many forging press purchases. The combination of efficiency mandates, operating cost pressure, and demonstrated hybrid and energy-recovery solutions is likely to make energy behavior a more explicit part of procurement evaluation. For commercial strategy, this creates opportunities for suppliers that can quantify energy savings, demonstrate compatibility with existing facility constraints, and offer solutions that do not sacrifice forming performance. It also creates an opportunity for operators to align equipment selection with broader cost-reduction and sustainability goals, especially where press replacements or major upgrades are already on the horizon. The uncertainty here lies in how quickly different regions and customer segments translate efficiency expectations into purchasing behavior, and whether standardized efficiency benchmarking becomes common enough to simplify comparisons across competing press technologies.
Automation-Integrated Press Platforms
A second major trend is the continued migration toward press platforms designed for integration with automated material handling, in-process monitoring, and adaptive control. The push comes from labor constraints, throughput ambitions, and the desire for more consistent process outcomes. Over the next several years, the most attractive press solutions are likely to be those that can function as part of a coordinated production system rather than as isolated mechanical assets. This opens commercial opportunities for vendors that can offer smoother integration pathways, clearer automation interfaces, and support for faster changeovers and lower manual dependency. For end-users, the opportunity is to reduce variability and increase asset utilization, but the risk is that automation ambition outpaces the readiness of the surrounding process, maintenance, and skills infrastructure. The market will likely reward customers and suppliers that treat automation as a system-level decision, not just a machine feature.
Regional Demand Divergence and Application Specialization
A third trend is the widening of regional demand profiles and the corresponding value of application specialization. While the market as a whole is growing at a moderate pace, demand intensity varies by region and by end-use sector. Areas experiencing broad industrial expansion are likely to drive higher volumes of standard and semi-custom equipment demand, while more mature markets may focus on replacement, modernization, and higher-value specialized forming capabilities. In parallel, applications in automotive, aerospace, and high-integrity industrial components are likely to continue supporting demand for presses that can deliver strong process control and repeatable quality. This environment favors suppliers and service strategies that can tailor offerings to regional realities and application-specific requirements. It also creates a risk: companies that rely too heavily on a single market or a single application may be exposed if local investment cycles shift or if sector demand patterns change faster than expected.
Actionable Guidance for Decision Makers
For manufacturers evaluating forging press strategy, the most important move is to align equipment selection with the operational priorities that will matter most over the asset's life. That means weighing energy performance, automation compatibility, service availability, and application fit alongside tonnage and price. Manufacturers should also consider whether a press platform can support future needs such as hybrid drive upgrades, better process monitoring, or integration with material handling without requiring a full replacement later. Suppliers and producers that take a total-cost and process-consistency view are more likely to emerge with installations that perform well under real production conditions rather than only under ideal specification conditions.
For investors, the opportunity lies in identifying the segments where technology differentiation, automation readiness, and regional demand alignment create durable advantages. The market's moderate overall growth does not mean uniform opportunity; value is likely to concentrate around vendors and end-users that can demonstrate measurable efficiency gains, serve high-integrity applications, or integrate press assets into broader automated production systems. Investors should also watch for signs of competitive repositioning around energy recovery and hybrid technologies, since these areas appear to be moving from demonstration to deployment. As with any industrial equipment sector, execution risk, installation complexity, and regional demand variability should be factored into any opportunity assessment.
For procurement and operations leaders, the priority is to treat press procurement as a systems decision. Transparency around energy consumption, automation interfaces, maintenance demands, and changeover complexity should be part of the evaluation process, not optional add-ons. Procurement teams should also seek evidence that proposed solutions have been validated in similar application environments, and they should ensure that vendor capabilities extend beyond equipment supply to include support for integration, commissioning, and ongoing performance optimization. In a market where operating constraints and workforce realities increasingly shape outcomes, the strongest purchasing decisions are likely to be those that balance technical capability with long-term operational practicality.
The forging presses market is not defined by sudden disruption, but by a steady accumulation of technology, efficiency, automation, and regional demand shifts that are reshaping what buyers expect and what suppliers must deliver. For decision makers who need to move beyond high-level market size figures and understand segment-specific dynamics, competitive positioning, and application-driven demand patterns, deeper market intelligence can make the difference between a reasonable capital plan and a strategically robust one. More detailed breakdowns, company-level profiles, and segment-focused scenario analysis are available in the full research report, where the broader macro context is translated into actionable detail for specific business decisions.
For detailed analysis of this topic, please visit the official page: Forging Presses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com